
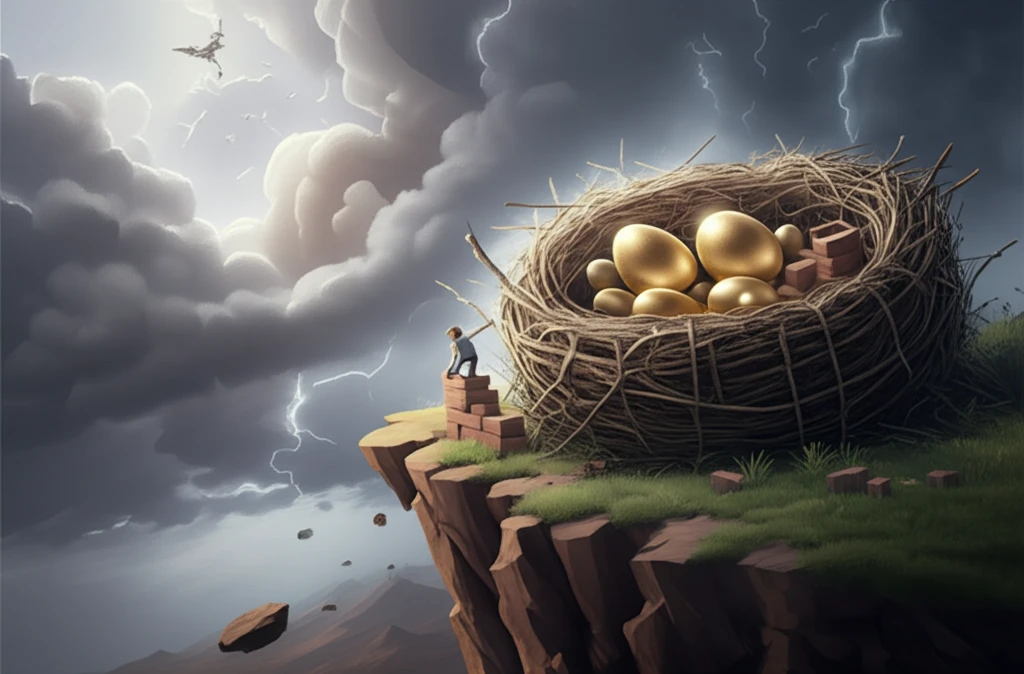
Is Your Nest Egg Safe? Understanding Ruin Probability in a Risky World
"Navigating the financial storms: How reinsurance and smart investing can protect your future from unexpected losses."
Imagine building a sandcastle, grain by grain, only to watch a sudden wave wash it all away. This feeling resonates with anyone who's worked hard to build financial security. The fear of losing it all – the nest egg, the retirement fund, the savings – is a universal concern. Insurance companies, who deal with risk daily, have a sophisticated way of analyzing this potential for loss, called 'ruin probability'. But what does it mean for you, and how can you use this concept to protect your financial future?
In essence, ruin probability is the chance that a company, or even an individual, will deplete their financial reserves within a certain timeframe. For insurance companies, it’s a critical metric for assessing their ability to pay out claims. They use complex models to estimate the likelihood that they'll run out of money, considering factors like investment returns, reinsurance strategies (insurance for insurers), and the types of risks they cover. While the math can get complicated, the core idea is simple: understand the risks, manage your resources, and minimize the chance of total loss.
This article will translate the complex world of ruin probability into practical insights you can use to protect your own financial well-being. We'll explore how insurance companies use these models, and, more importantly, how you can apply similar thinking to your investments and savings. Whether you're planning for retirement, managing a small business, or simply trying to secure your family's future, understanding ruin probability can empower you to make smarter, more resilient financial decisions.
Why the Odds of Running Out Are Hard to Pin Down
Quantifying the odds that a retirement nest egg runs out before the saver does depends heavily on unknowable future investment returns and spending decisions, so any precise figure is inherently uncertain. Widely cited planning guidance such as 'safe withdrawal rates' rests on historical market experience rather than on guarantees. Ruin probability research helps translate that uncertainty into an explicit, model-based risk estimate. Because reliable, broadly agreed statistics on general-population retirement ruin are limited, any specific number should be treated cautiously and as conditional on assumptions.
Classical Models Extended Into a Risky Investment World
In the standard approach to ruin theory, mathematical models in actuarial science and applied probability describe an insurer's vulnerability to insolvency, with the probability of ruin, the surplus immediately prior to ruin, and the deficit at ruin time as the key quantities of interest. Because reserves can also be eroded by investment losses, modern models combine classical frameworks with asset price dynamics developed in mathematical finance, in effect treating risky investments as producing stochastic interest rates. Some newer extensions let the parameters of the investment process depend on a Markov process representing random changes in economic and financial conditions. A notable limitation is that exact answers are rarely available, so much of the literature instead seeks conditions on the asymptotic behaviour of the ruin probability, such as the existence of a Lundberg exponent guaranteeing power-function behaviour.
From the Coin Toss to Lundberg Bounds
Risk of ruin is a long-standing concept across gambling, insurance, and finance, defined as the likelihood of losing all of one's investment capital or exhausting a bankroll below the minimum needed for further play, as with the simple example where betting everything on a coin toss carries a 50% probability of ruin. Within insurance mathematics, the Lundberg bound—an upper bound on the ruin probability—has played an important role, even though relatively few of the many modern risk model variants admit a Lundberg-type inequality. Over time, a rich toolbox has developed for calculating, approximating, or asymptotically analysing ruin probabilities, spanning probability arguments, complex analysis, Wiener-Hopf factorisation, and the analysis of integro-differential equations.
Decoding Ruin Probability: What Factors Increase Your Risk?
Several factors contribute to the likelihood of financial ruin. Understanding these can help you identify vulnerabilities and take proactive steps to mitigate them. Here are some key elements that both insurance companies and individuals need to consider:
- Unexpected Expenses: Unforeseen events like medical emergencies, job loss, or major home repairs can quickly drain your financial reserves.
- Inadequate Insurance Coverage: Being underinsured leaves you vulnerable to significant financial setbacks if disaster strikes.
- Poor Debt Management: High levels of debt, especially with high-interest rates, can create a constant drain on your resources, increasing the risk of ruin.
- Inflation: The rising cost of goods and services can erode the purchasing power of your savings, making it harder to maintain your financial stability.
- Longevity Risk: Living longer than expected can deplete retirement savings, especially if you haven't adequately planned for extended living expenses.
Heavy Tails, Risky Portfolios, and Asymmetric Payoffs
Recent research increasingly models an insurer's surplus as invested in a portfolio that combines a risk-free asset and a risky asset. For heavy-tailed claim sizes together with delayed claims, one recent study derives asymptotic formulas for the finite-time ruin probability as the initial surplus approaches infinity. Separately, work on strategies with asymmetric payoffs—common in venture capital, tail-risk hedging, and derivative strategies—considers investments with positive, zero, or negative expected returns and obtains analytic results for ruin probabilities, expected final wealth, and game duration. Other investigations continue the theme of reserves invested in risky assets whose price dynamics follow a geometric Brownian motion modulated by a random environment.
The Limits of Ruin Models in Practice
Despite their mathematical elegance, ruin models are subject to real limitations and can produce a false sense of precision when applied to actual portfolios. Any calculation rests on assumptions about claim distributions, investment dynamics, dependencies, and the parameters chosen to represent them, all of which must be estimated from data and can shift with market conditions. A computed ruin probability is therefore best read as a conditional scenario estimate rather than an objective forecast of the future. Practitioners accordingly caution against treating any single modelled figure as a definitive measure of safety.
Trading Off Tractability and Realism
The different approaches to measuring ruin risk each carry distinct strengths, and direct comparisons are not straightforward. Simple bound-based and closed-form results are transparent and easy to communicate, but they typically rely on simplifying assumptions about how claims and investments behave. More realistic models that incorporate risky investments, heavy-tailed losses, and dependencies are far harder to solve and generally deliver asymptotic or numerical answers instead of exact figures. In practice, the right method depends on the question being asked: a rough bound may be enough for broad strategic planning, while detailed stochastic models are better suited to regulatory capital and pricing decisions.
Securing Your Financial Future: It's About More Than Just Luck
Financial security isn't about eliminating risk altogether; it's about understanding, managing, and mitigating those risks to build a resilient future. By adopting strategies like diversifying investments, securing adequate insurance coverage, and practicing sound debt management, you can significantly reduce your own ruin probability. Remember, like insurance companies, you have the power to assess your vulnerabilities and take proactive steps to safeguard your financial well-being.
Ruin Risk as a Conditional, Comparative Measure
Ruin probability analysis quantifies the risk that an insurer's surplus falls below zero, signalling insolvency, with the classical Cramér–Lundberg framework treating the arrival of claims within such a surplus process. Researchers continue to extend this foundation by adding risky investments, random environments, and dependence between claims and investment returns so that the models better reflect today's financial reality. The synthesis emerging from current literature is that ruin risk is a moving target shaped as much by investment volatility and systemic shocks as by underlying underwriting experience. Expert commentary accordingly frames ruin probability as a comparative and conditional measure, useful for ranking strategies and calibrating capital buffers rather than for issuing single definitive safety verdicts.
Richer Models, Behavioral Realism, and Computational Power
Looking ahead, the frontier of ruin research is likely to lie in models that capture how modern portfolios behave under stress, including heavy-tailed losses, delayed claim settlements, and regime shifts in the economic environment. Advances in computing and numerical methods should make it feasible to estimate and apply these richer models to individual retirement planning as well as institutional solvency. Integrating behavioural factors—how people respond to losses by changing spending or investment—could make ruin estimates considerably more realistic. Wherever it leads, the next generation of models will still have to contend with the trade-off between realism and tractability that has defined the field since its founding.
Systemic Shocks and the Rise of Asymmetric Strategies
From a systemic perspective, a continuous-time risk model in Applied Mathematics and Computation shows how insurance claims and investment return jumps can be shocked by common systematic risk factors, with random delays often occurring before insurers settle incurred claims. Such co-movement between an insurer's liabilities and its investment returns means ruin risk can rise across many institutions at once precisely when financial markets are stressed. Related work on strategies with asymmetric payoffs—venture capital, tail-risk hedging, and derivative strategies—shows that ruin behaviour depends on whether each investment carries a positive, zero, or negative expected return. Together these strands suggest that ruin is not merely an idiosyncratic, firm-level concern but a challenge intertwined with broader market dynamics and correlated shocks.
What Ruining Out Means in a Human Life
Behind the mathematics, ruin risk carries deeply personal stakes: once a retiree's resources hit zero, future earnings usually cannot restore them, and the fear of running out shapes spending, saving, and investment behaviour. Quantitative measures of ruin probability can help people weigh trade-offs—such as guaranteed income versus growth-oriented assets—in a more informed way. At the same time, the uncertainty built into the models means that even careful planning offers no ironclad guarantee. Communicating these probabilities honestly, with their assumptions made explicit, may ultimately matter as much as the calculations themselves.