
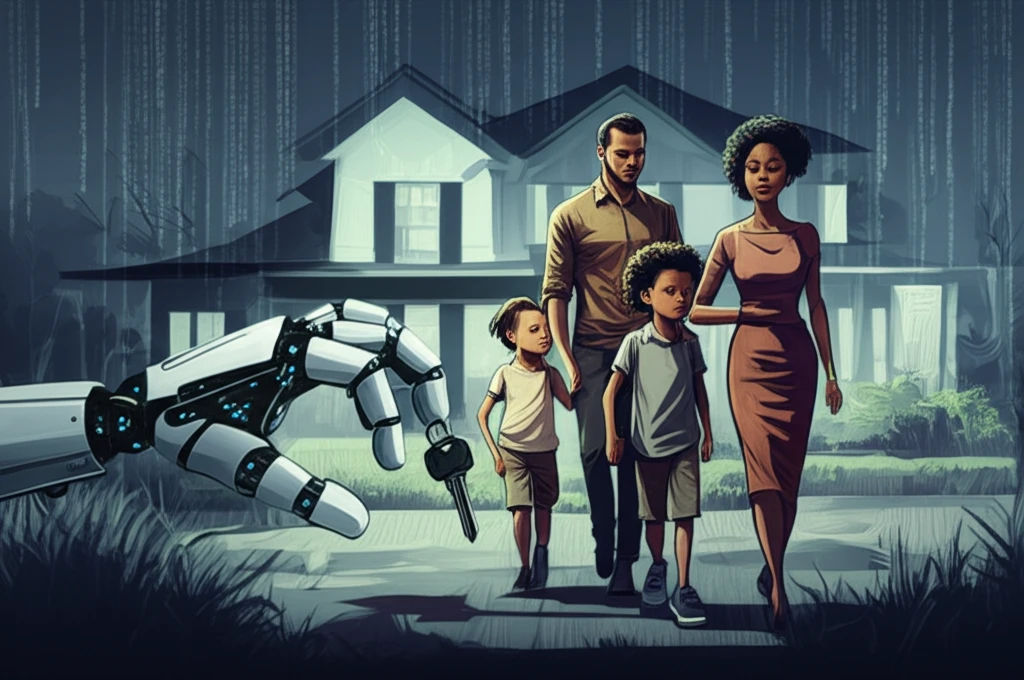
Decoding Bias: Can AI Really Make Fairer Lending Decisions?
"Explore how AI models inherit and amplify biases in mortgage lending, and discover innovative de-biasing methods that could revolutionize financial fairness."
In an era increasingly shaped by algorithms, the promise of artificial intelligence (AI) to automate and streamline decision-making processes is both exciting and fraught with challenges. One area where AI is making significant inroads is in the financial sector, particularly in mortgage lending. The appeal is clear: AI can process vast amounts of data quickly, potentially leading to faster and more efficient loan approvals. However, this automation raises a critical question: Can AI truly make unbiased decisions, or does it simply perpetuate existing societal inequalities?
The challenge lies in the data used to train these AI models. If the historical data reflects biased lending practices, the AI will inevitably learn and replicate these biases, even if protected characteristics like race or ethnicity are explicitly excluded from the model. This can lead to a situation where AI, intended to be a neutral arbiter, ends up reinforcing discriminatory patterns in lending.
A recent study delves into this issue, exploring various methods to de-bias AI models used in mortgage application approvals. The research investigates how AI models inherit biases, even when seemingly objective criteria are used, and compares different techniques to mitigate these biases, offering insights into the potential and limitations of AI in promoting fairer lending practices.
AI's Growing Footprint in Decision-Making
Artificial intelligence is defined as the capability of computational systems to perform tasks typically associated with human intelligence, including learning, reasoning, problem-solving, perception, and decision-making. Major AI developers such as OpenAI, Google, and Anthropic have deployed large-scale systems capable of handling complex real-world tasks like writing, coding, planning, and brainstorming. As these general-purpose AI tools become embedded in everyday workflows, their potential application in high-stakes domains like lending is expanding, raising questions about fairness and accountability in automated decisions. Reference URL 1: https://en.wikipedia.org/wiki/Artificial_intelligence | Reference URL 2: https://openai.com/
Development Platforms and the Pace of Prototyping
Google's AI Studio provides a platform for building and experimenting with AI applications, suggesting a maturing development ecosystem. However, the rapid prototyping of AI-powered tools often outpaces the development of safeguards, particularly in regulated industries like finance. While the tooling to create lending-decision models is more accessible than ever, the accepted methods for auditing bias or ensuring equitable outcomes remain fragmented and inconsistent across organizations. Reference URL 1: https://aistudio.google.com/
A Brief History of AI and Fairness
The idea that machines could make judgments about creditworthiness dates back to early credit-scoring systems, though the infusion of AI into lending decisions is a more recent phenomenon. Researchers and regulators have long debated whether algorithmic systems inherit or even amplify the biases present in historical training data. While significant foundational work has been done on algorithmic fairness, consensus on universal standards for measuring and mitigating bias in lending remains elusive.
The Ghost in the Machine: How AI Learns to Discriminate
The study begins by demonstrating how easily an AI model can replicate bias, even without explicitly using protected characteristics. Researchers simulated bias against Hispanic and Latino applicants by artificially altering approval decisions in a real-world mortgage dataset. This manipulation ensured that the AI model would encounter biased data during its training phase.
- Correlation Exploitation: AI can identify correlations between seemingly neutral variables and protected characteristics, using these as proxies for discrimination.
- Data Reflection: If historical data is biased, AI models trained on that data will inevitably learn and replicate those biases.
- Subtle Patterns: AI can uncover and amplify subtle discriminatory patterns that humans might miss.
Where the Evidence Stands
The latest body of research on AI in lending suggests that algorithmic models can reduce some forms of human bias but are not inherently free from discrimination themselves. Studies have found that even when protected attributes like race are excluded, proxy variables such as zip code or purchasing patterns can reintroduce discriminatory outcomes. The field is actively debating whether AI-driven lending decisions truly offer a net improvement over traditional human judgment, with results varying across different lending contexts and demographic groups.
Known Failures and Skepticism
Skeptics of AI-driven lending fairness point to documented cases where automated systems have denied loans or offered worse terms to minority applicants at disproportionate rates. Critics argue that training data drawn from historically inequitable lending practices means AI systems may simply replicate existing inequalities at scale. Some researchers caution that the opacity of modern machine learning models makes it difficult for both regulators and applicants to understand why a particular decision was made, undermining accountability.
AI vs. Traditional Lending Judgments
Comparing AI-driven lending decisions to traditional human underwriting reveals a mixed picture: AI can process far more data points and do so with greater consistency, but it lacks the contextual judgment that a human underwriter might bring to edge cases. Early evidence suggests that in some controlled scenarios, AI models achieve more equitable approval rates than human loan officers, but only when they are explicitly trained and audited for fairness. Without deliberate intervention, AI models tend to perform comparably to or worse than human decision-makers in terms of equitable outcomes.
The Path to Fairer Algorithms
The journey toward truly fair AI in mortgage lending is ongoing. The findings underscore the importance of contextual awareness and careful consideration of the different forms that bias can take. By implementing appropriate de-biasing techniques and continuously monitoring AI models for discriminatory outcomes, the industry can move closer to a future where technology promotes, rather than hinders, equal access to financial opportunities. The key is to understand the nuances of how AI learns and to proactively address the potential for bias at every stage of the development and deployment process.
Weighing the Evidence
The evidence to date suggests that AI has genuine potential to make lending decisions fairer, but only under conditions that few real-world implementations currently meet. Experts generally agree that transparency, diverse training data, and independent auditing are prerequisites for responsible deployment, yet adoption of these practices remains inconsistent. Ultimately, the technology is only as equitable as the goals and safeguards embedded into its design.
What Comes Next
Looking ahead, the trajectory of AI fairness in lending will likely be shaped by evolving regulatory frameworks and advances in explainable AI research. Emerging techniques such as causal inference models and adversarial debiasing offer promising avenues for reducing discriminatory outcomes in real time. However, whether these technical advances will be adopted broadly—and enforced meaningfully—remains an open question.
AI's Broader Social Responsibility
Google AI has stated a commitment to building useful AI tools that enrich knowledge and help solve complex challenges, reflecting a broader industry aspiration to make AI beneficial for everyone. However, translating that aspiration into fair lending practice requires grappling with systemic issues such as historical data inequities and uneven access to technology. The challenge is not purely technical; it is deeply intertwined with structural inequalities in housing, employment, and wealth that shape the data AI systems consume. Reference URL 1: https://ai.google/
Lending Decisions Affect Real Lives
Behind every lending algorithm are people whose access to housing, education, and business capital depends on the outcome, making accuracy and fairness a deeply human concern. While AI answer engines and research tools can help individuals better understand loan terms or challenge decisions, they do not replace the need for equitable systems at the institutional level. The real-world impact of biased AI lending decisions extends beyond the individual applicant, reinforcing cycles of economic inequality across communities. Reference URL 1: https://www.perplexity.ai/