
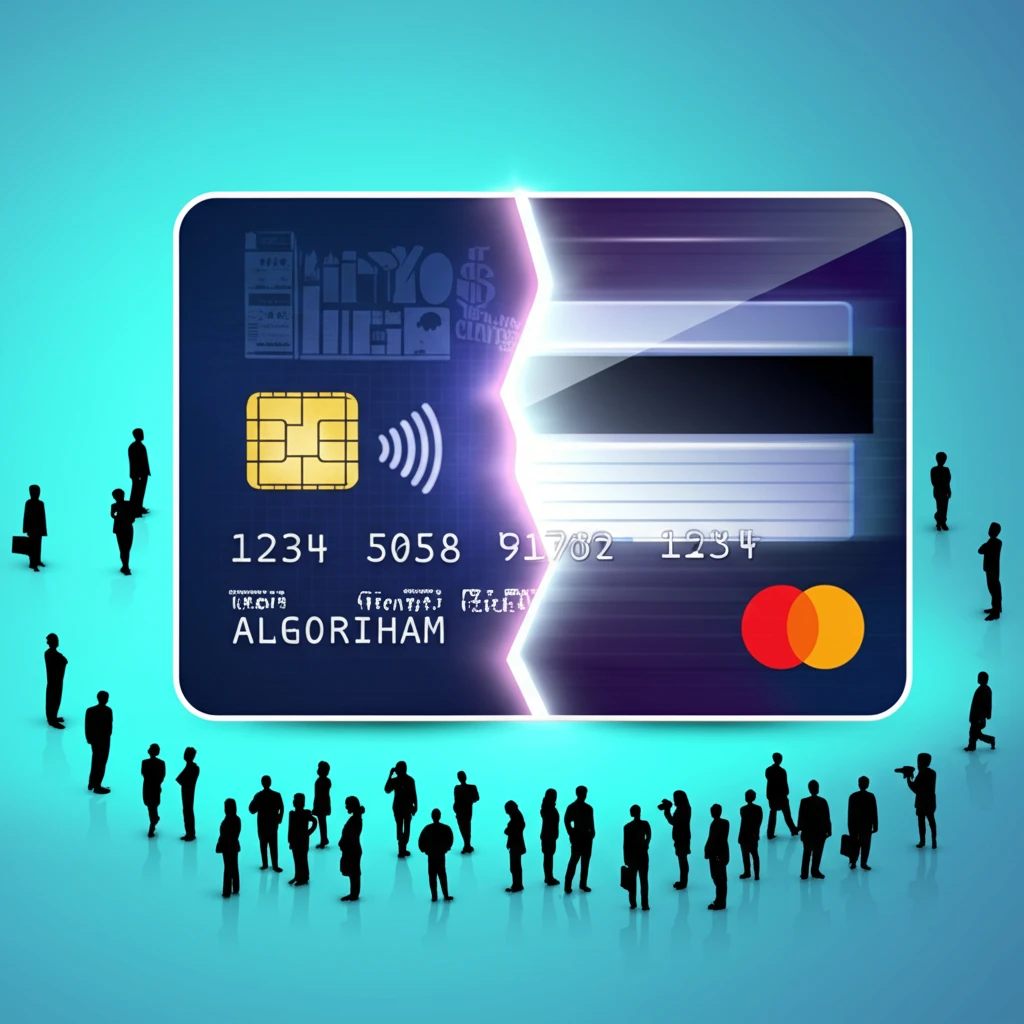
Credit Lending: Can AI Really Be Fair? How to Fix Hidden Biases
"Discover how a new AI technique called Subgroup Threshold Optimization (STO) can reduce discrimination in credit lending models by up to 90%."
In today's financial landscape, Artificial Intelligence (AI) is increasingly used to automate credit lending decisions. While AI promises efficiency and accuracy, recent studies reveal a troubling side: these systems can perpetuate biases, unfairly disadvantaging certain groups. Imagine a world where your loan application is unfairly denied not because of your credit history, but because of your gender or other protected characteristic. This is the reality that many face due to hidden biases in AI lending models.
The problem stems from the data used to train these AI systems. If the data reflects historical biases, the AI will learn and amplify these biases, leading to discriminatory outcomes. For example, if past lending practices favored men, an AI trained on this data might unfairly reject creditworthy women. This isn't just unethical; it can also lead to significant financial losses and legal repercussions for lending institutions.
Fortunately, researchers are developing innovative solutions to combat AI bias. One promising technique is Subgroup Threshold Optimization (STO). This method doesn't require altering the original training data or the AI algorithm itself. Instead, it fine-tunes the decision-making thresholds for different subgroups to minimize discrimination and ensure fairer outcomes for all.
Current Statistics & Impact
Artificial intelligence denotes computational systems capable of performing tasks associated with human intelligence, such as learning, reasoning, problem-solving, perception, and decision-making. Major research efforts, including those by OpenAI, are pursuing artificial general intelligence systems that can solve human-level problems across diverse domains. Generative AI assistants like Google Gemini extend these capabilities to practical applications such as writing, planning, and brainstorming. Platforms such as ChatGPT demonstrate AI's utility in answering questions, creating content, and coding, reflecting its growing integration into everyday workflows.
Standard Approach, Accepted Methods & Their Limitations
The landscape of AI development encompasses diverse methodological approaches, from deep learning architectures to symbolic reasoning systems, each carrying distinct tradeoffs. Researchers continue to navigate challenges in balancing performance, safety, and interpretability across different paradigms. The field's rapid evolution means that accepted practices and identified limitations frequently shift with new findings and application contexts.
Historical Perspective, Milestones, Foundational Discoveries
Google AI Studio provides tools for generating photorealistic window views conditioned on live weather and specific locations, enabling novel approaches to spatial intelligence. The platform supports managing virtual metropolises and fulfilling tasks provided by Gemini, representing milestones in interactive AI world-building. These capabilities reflect foundational discoveries in connecting generative models with practical environmental modeling and task execution.
Unveiling the Hidden Biases in AI Lending Models
AI bias in credit lending can manifest in various ways. Historical bias occurs when past societal prejudices seep into the data, influencing the AI's decisions. Measurement bias arises when using unsuitable data as proxies for real-world factors. For example, using zip code as a proxy for race can lead to discriminatory lending practices.
- Historical Bias: Past prejudices reflected in training data.
- Measurement Bias: Using inaccurate proxy data.
- Representation Bias: Training data not representative of the population.
- Aggregation Bias: Losing unique features by combining data improperly.
- Evaluation Bias: Ineffective metrics that reward biased outcomes.
Latest Research and Reviews
The AI research ecosystem produces a continuous stream of new model architectures, training methodologies, and benchmark evaluations, with findings often specialized to particular domains or tasks. Review literature maps advances in areas such as multimodal reasoning, efficiency improvements, and safety frameworks, though conclusions depend on evolving evaluation standards. The pace and scope of published work make comprehensive synthesis challenging, as results may not generalize beyond specific experimental conditions.
Counter Arguments and Failures
Critiques of AI systems frequently highlight concerns regarding robustness, reliability, and the fidelity of generated outputs, including instances of unexpected behavior or hallucination in generative contexts. Empirical analyses and deployment experiences have identified vulnerabilities across various model sizes and architectures, prompting ongoing reconsideration of risk assessment frameworks. These counter arguments underscore the importance of rigorous testing, transparent documentation, and cautious rollout practices in real-world settings.
Comparative Analysis
Comparative studies of AI architectures typically evaluate tradeoffs in capability, computational cost, and generalization performance across tasks such as classification, generation, and reasoning. Different model families and training objectives yield varying profiles of strength and weakness, influencing selection criteria for application-specific deployment. Empirical benchmarks and theoretical analyses contribute to a nuanced understanding of relative strengths, though no single approach dominates all relevant metrics.
The Future of Fair Lending with AI
Subgroup Threshold Optimization (STO) offers a promising path toward fairer AI lending. By fine-tuning decision thresholds for different subgroups, STO minimizes discrimination without requiring extensive changes to existing AI systems. This approach is easy to understand, flexible, and can be implemented by non-experts, making it a practical solution for the credit lending industry. As AI continues to transform the financial landscape, techniques like STO are essential for ensuring that these technologies promote fairness and opportunity for all.
Synthesis & Expert Commentary
Interdisciplinary expert commentary spans assessments of AI's societal benefits, risk profiles, and governance requirements, drawing on perspectives from computer science, philosophy, economics, and domain-specific fields. Synthesis of these viewpoints often reveals convergence on the need for responsible development pipelines, while disagreements persist on prioritization, timescales, and the appropriate degree of regulatory intervention. The complexity of aligning increasingly capable systems with diverse human values and institutional frameworks remains a central theme.
Future Outlook & Next Frontiers
Future research directions in AI anticipated by experts include advances in reasoning and planning capabilities, improved multimodal integration, and refined approaches to alignment and interpretability. Emerging frontiers also encompass efficient training paradigms, neurosymbolic methods, and infrastructure for distributed, trustworthy model deployment. These trajectories reflect ongoing efforts to extend current capabilities while addressing persistent technical and ethical considerations.
Broader Context & Systemic Challenges
Google AI emphasizes a commitment to enriching knowledge, solving complex challenges, and supporting human growth through the development of useful AI tools and technologies. This mission-oriented framing positions AI as a contributor to knowledge ecosystems and problem-solving domains beyond purely commercial applications. The stated focus on building helpful systems reflects broader institutional recognition of AI's potential role in addressing substantive societal and technical challenges.
The Human Element & Real-World Impact
Perplexity operates as a free AI-powered answer engine delivering accurate, trusted, and real-time responses to user questions across diverse topics. By providing timely information retrieval, the platform illustrates how AI interfaces are reshaping everyday information access and decision-making contexts. Its design reflects wider trends in deploying generative AI for practical utility in knowledge-work and personal inquiry scenarios.