
Unveiling the Shadows: How Offshore Financial Centers Impact Your World
"Dive into the complex world of offshore finance and uncover how these hidden conduits and sinks shape the global economy, affecting everything from corporate taxes to international investments."
In today's interconnected world, multinational corporations operate complex webs of parent companies and subsidiaries to manage their global operations. Facilitating these intricate structures are offshore financial centers (OFCs), jurisdictions offering low taxation and lenient regulation. While they can be useful for businesses, OFCs are increasingly scrutinized for enabling tax avoidance and other activities, raising important questions about their role in the global economy.
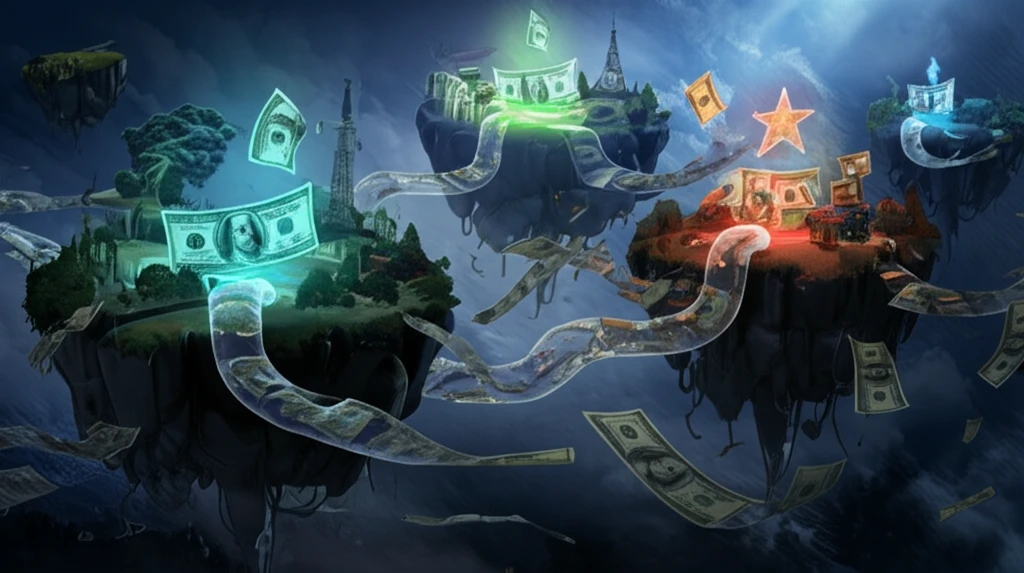
Understanding OFCs is crucial. These financial hubs play a significant role in international capital flows, acting as both 'conduits' and 'sinks.' Sink-OFCs attract and retain foreign capital, functioning as tax havens where money accumulates. Conduit-OFCs, on the other hand, serve as intermediate destinations for international investments, enabling the transfer of capital with minimal taxation.
This article explores the hidden world of OFCs, revealing how they operate within the global corporate ownership network. By examining the roles of both sink and conduit jurisdictions, we can better understand the impact of these financial centers on international investment, tax policies, and the global economy.
The Scale and Mechanics of Offshore Secrecy
Tax havens attract trillions of dollars in offshore assets by offering favorable tax conditions, banking secrecy, and minimal regulation, though the exact figures vary by dataset and definition. Rather than a single official list, researchers now separate official listings, index-based risk scores, low-tax special regimes, mainstream planning hubs, and watchlist history, reflecting how jurisdictions differ in function and scrutiny. Public research initiatives, such as the EU Tax Observatory's Atlas of the Offshore World, aim to improve the quality of data available for studying tax evasion and avoidance, while broader guides trace both corporate and individual use of offshore centers and the compliance frameworks that now govern them (FATCA, CRS). Together these sources suggest that the true scale of offshore activity depends heavily on how one classifies a jurisdiction, which helps explain wide variation in reported impact.
How Offshore Activity Is Measured and Why Estimates Differ
Common approaches to studying offshore financial centers rely on official listings, index-based risk scores, and balance-of-payments or cross-border banking statistics, each of which captures a different slice of the phenomenon. No single accepted methodology yet exists, and measurement is complicated by definitional disagreements over what qualifies as a tax haven, by missing or opaque data, and by the difficulty of distinguishing legal avoidance from illegal evasion. Academic and policy research increasingly cautions that estimates of offshore wealth are highly sensitive to methodology, so published figures are best treated as indicative ranges rather than precise counts. Readers should therefore interpret any headline statistic on offshore capital with caution and look for how a given source defines and measures its data.
From Simple Origins to the Panama Papers
Histories of offshore finance trace its roots from early uses of foreign territory for tax and wealth purposes through the emergence of modern offshore zones, with some accounts extending the timeline from ancient practices to the present. Banking statistics from the Bank for International Settlements indicate that since the early 1980s roughly half of all international banking assets and liabilities have been routed through jurisdictions commonly associated with offshore finance. The Panama Papers stand out as a landmark disclosure that exposed the hidden structures used by wealthy individuals and corporations, reshaping public understanding of tax havens and their role in the global economy. Historical accounts generally agree that periods of crisis, regulatory change, and advances in corporate mobility were key factors driving the growth and evolution of these jurisdictions.
What Are Offshore Financial Centers and Why Do They Matter?
Offshore Financial Centers (OFCs) are essentially jurisdictions that provide financial services to non-residents on a scale that is incommensurate with the size and financing of their domestic economies. This definition highlights a key characteristic: OFCs handle a disproportionately large amount of financial activity compared to their local economic activity. Understanding the different types of OFCs—sink and conduit—is essential to grasping their global impact.
- Tax Minimization: Companies use sink-OFCs to legally reduce their tax obligations.
- Asset Protection: These centers offer a layer of privacy and protection for assets.
- Accumulation of Wealth: Sink-OFCs serve as destinations where capital can accumulate with minimal taxation.
New Evidence on Havens, Productivity, and a Shifting Market
Recent network-based research suggests that multinational enterprises use tax havens to benefit from international tax arbitrage and improve capital efficiency, while also noting that these activities may distort global productivity and investment patterns. Analyses of the market for tax havens point to a rise across the twentieth century driven by interacting supply and demand forces, with new datasets helping scholars date and explain that growth. At the same time, journalistic and industry reporting describes a great offshore tax exodus, in which traditional secrecy havens lose their grip under mounting global scrutiny from international tax reforms and transparency measures. Other reporting contends that the classic offshore jurisdictions are not vanishing but evolving, combining zero-tax frameworks with political stability and digital mobility in a fragmenting global economy marked by rising sovereign debt and OECD-led pressure.
When the Offshore Model Falls Short
Critics of offshore finance argue that well-publicized transparency initiatives have not fully delivered on their promises, and that enforcement gaps, definitional loopholes, and uneven international cooperation continue to undermine reform efforts. Some analysts also observe that tax havens face practical limitations, including reputational damage, tightening compliance costs, and pressure from regulators that can erode the very advantages they once offered. Meanwhile, defenders point out that much offshore activity is legal and can support legitimate asset protection and capital mobility, though even they acknowledge that abuses persist and hard data remains incomplete. Overall, assessments of whether the offshore model is failing are mixed, with outcomes depending heavily on jurisdiction, time period, and the interests of the source making the claim.
Tax Havens Versus Offshore Financial Centres
Industry guides distinguish tax havens, defined primarily by low or zero taxation and banking secrecy, from offshore financial centres, which may offer broader financial services, asset protection, and operational efficiency as part of their appeal. As regulatory standards have evolved, the boundary between the two has become more nuanced, with transparency, compliance, and international cooperation now central to how these jurisdictions operate and are classified. Ethical debates focus on whether such centers facilitate aggressive tax avoidance and evasion at the expense of public resources, with critics arguing that wealthy individuals and corporations reduce tax liabilities improperly. At the same time, sources emphasize the legitimate uses of these structures, including tax planning and financial privacy, illustrating that evaluations depend heavily on the user's perspective and the legal status of the activities involved.
The Future of Offshore Finance: Transparency and Regulation
As the world becomes more interconnected, the role of OFCs will remain a critical topic of discussion. The ongoing debate surrounding tax avoidance, regulatory arbitrage, and the potential for illicit financial flows will continue to drive efforts to increase transparency and strengthen international cooperation. By understanding the dynamics of OFCs, we can better navigate the complexities of the global financial landscape and work towards a more equitable and sustainable economic future.
Weighing the Expert Evidence
Expert commentary describes the world of offshore finance as a deeply embedded element of the global financial system, where a longstanding web of secrecy has historically shielded arrangements from public view. Investment-oriented experts frame tax havens primarily in terms of strategies for growing and protecting wealth, emphasizing legal considerations and the advantages of low-tax jurisdictions for the savvy investor. Academic-style reviews of offshore foreign direct investment add a cautionary note, reporting that such routing may be associated with productivity distortions even as it improves capital efficiency for firms. Taken together, expert analyses converge on a picture of offshore centers that are neither pure engines of wrongdoing nor neutral administrative tools, but rather high-stakes institutions whose benefits and costs depend on how and by whom they are used.
Where the Offshore Landscape Is Heading
The offshore landscape appears to be entering a period of transformation, driven by international tax reform, digital mobility, and tightening transparency requirements, though the pace and direction of change remain uncertain. While some analysts expect traditional havens to decline under sustained regulatory pressure, others foresee jurisdictions adapting by offering new combinations of low tax, stability, and financial innovation that keep capital flowing offshore. Emerging technology and remote administration could also make secrecy structures easier to establish and harder to trace, creating new enforcement challenges. Forecasts are inherently speculative on this topic, and most sources hedge their projections, acknowledging that outcomes will depend on politics, enforcement, and how rapidly governments cooperate.
Offshore Finance as a Systemic Issue
Offshore finance is increasingly discussed not as an isolated tax problem but as a systemic feature of the global economy, intertwined with inequality, sovereign debt, and the structure of international capital flows. Analysts tie the persistence of havens to rising fiscal pressure on governments, the mobility of digital capital, and gaps in international coordination that leave room for regulatory arbitrage. Reforms such as common reporting standards and disclosure regimes are widely seen as partial fixes that reduce but do not eliminate loopholes. The systemic framing suggests that lasting solutions will require coordinated trade-offs among national interests, raising challenges that are as much political and institutional as they are technical.
Public Consequences Behind the Balance Sheets
Beyond balance sheets, offshore finance has real-world consequences for ordinary citizens, shaping public budgets, the fairness of tax systems, and perceptions of institutional legitimacy. When wealth is shielded from taxation, the resulting revenue shortfalls can affect public services and place a larger share of the tax burden on those with fewer options to avoid it. High-profile leak disclosures have also shifted public sentiment, making matters once hidden more visible and fueling demands for accountability. These human impacts are difficult to quantify precisely, and claims about who ultimately bears the costs remain contested, but the theme recurs throughout expert and journalistic treatments of the offshore economy.