
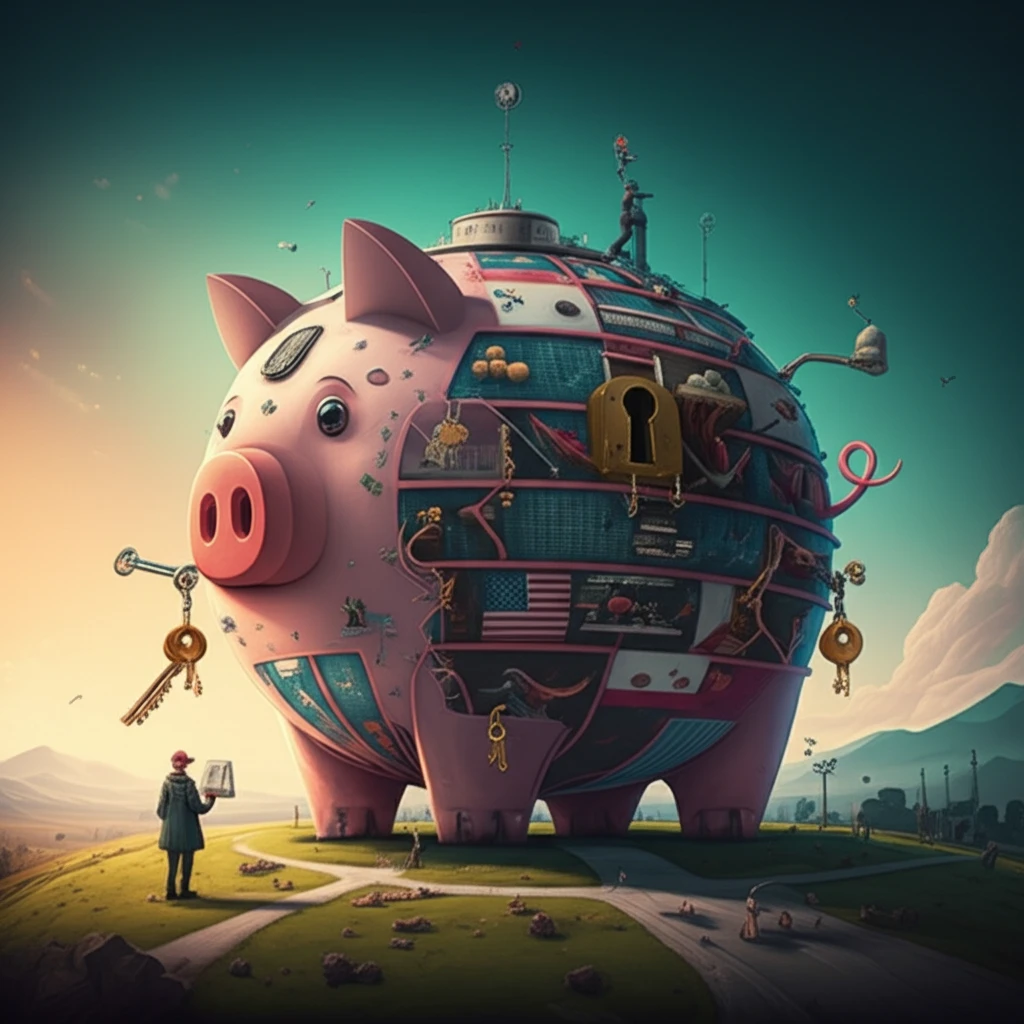
Tax Breaks for the World's Biggest Companies: Fair Deal or Highway Robbery?

"Decoding the Debate Around Multinational Tax Policies and What They Mean for You"
Imagine a game where the players are countries, and the prize is attracting the world's most powerful companies. To win, some countries offer tax breaks and incentives. This can spark intense debates: Are these policies smart moves to boost the economy, or are they unfair advantages that let multinationals avoid paying their fair share?
The question of how to tax multinational corporations is far from simple. It touches on economics, fairness, and the delicate balance of power between nations and global giants. Understanding the key arguments is essential, whether you're an economist, a policymaker, or simply someone interested in how the global economy works.
This article explores the intricate world of multinational tax policies, drawing from the research paper 'Optimal National Policies towards Multinationals when Local Regions Can Choose between Firm-Specific and Non-Firm-Specific Policies' by Osiris J. Parcero. We'll break down the core concepts, highlight the key debates, and discuss the potential implications for businesses, governments, and you.
Why the Stakes Matter
Tax incentives for very large companies can affect public revenue, investment decisions, and perceptions of fairness. Their effects vary by jurisdiction, industry, and the conditions attached to each incentive. Without comparable, verified figures, the overall impact should be assessed cautiously rather than reduced to a single universal conclusion.
Platform-Based Distribution
The listed sources describe online platforms that distribute free adult video content, including XVIDEOS, Pornhub, XNXX, and QORNO.COM. Their descriptions emphasize large catalogs, searchable categories, free access, and, in XNXX's case, more than 10 million videos. These sources document how the platforms present their services, but they do not provide evidence about tax incentives, corporate taxation, or the limitations of accepted methods for evaluating tax breaks.
Defining Luxury Goods
The U.S. Export Administration Regulations identify tobacco and tobacco products, luxury watches, and apparel and fashion items as examples of luxury goods. Economic definitions generally describe a luxury good as one whose demand rises more than proportionally as income increases. The listed sources therefore connect luxury goods both to regulatory classification and to income-sensitive consumer demand.
Why Do Countries Offer Tax Breaks to Multinationals?
The main goal is to attract foreign direct investment (FDI). Countries hope that by offering lower taxes, they can convince large companies to set up shop within their borders. This, in turn, can lead to job creation, economic growth, and the transfer of new technologies.
- Firm-Specific Policies: These are tailored deals negotiated directly with a company, offering them unique tax advantages. Think of it as a custom-made suit, designed to fit one particular client.
- Non-Firm-Specific Policies: These are broader tax breaks or incentives that apply to any company that meets certain criteria, regardless of size or industry. This is like buying something off the rack – it's available to anyone who qualifies.
The Meaning of Irreplaceability
The listed Korean-language sources translate or explain the English term "irreplaceable" as something that cannot be substituted or is uniquely important. Examples include family, valuable team members, natural resources, and ecosystems. These materials are language references rather than research reviews of corporate tax policy, so they support terminology but not conclusions about tax breaks.
Limits of the Available Evidence
The supplied material does not document specific counterarguments, failed tax incentives, or company-level outcomes. A balanced assessment would need evidence on both the intended benefits and the costs or unintended effects of tax breaks. In the absence of that evidence, claims that a particular policy succeeded or failed should remain qualified.
A Missing Comparison
The supplied sources do not provide comparable tax rates, incentive packages, jurisdictions, companies, or outcome measures. Meaningful comparison would require consistent definitions and data across the cases being evaluated. Any ranking of countries or companies would therefore go beyond the available material.
The Bottom Line: A Continuing Debate
The debate over multinational tax policies is likely to continue. There are valid arguments on both sides. Tax incentives can be a powerful tool for attracting investment and promoting economic growth, they can also create unfair advantages and lead to a loss of tax revenue for governments. Striking the right balance is essential for creating a fair and sustainable global economy.
Small Organ, Large Function
The listed sources agree that the human heart is a relatively small part of the body but performs a vital function. One source reports that it represents approximately 0.3% of total body mass in an average 80-kilogram adult, while another gives a typical adult weight of 230 to 340 grams. The sources differ in how they describe average heart weight by sex, so specific weight estimates should be treated as ranges rather than a single universal figure.
Evidence Before Forecasts
The supplied sources do not contain projections about future tax policy, corporate investment, or emerging incentive models. Any forecast about the next generation of tax breaks would require current policy data and clearly stated assumptions. Until those are available, future developments should be presented as possibilities rather than established trends.
Community Knowledge Sharing
The listed HubSpot sources describe a community built around product questions, feature requests, peer knowledge sharing, and educational examples. One announcement says HubSpot users could opt into a public beta for a new theme beginning June 30, 2026. These sources illustrate how a company-supported community can connect users with guidance, but they do not establish broader systemic effects of corporate tax policy.
A Local Retail Presence
The supplied sources identify Kohl's stores in Dubuque, Iowa, including locations associated with Northwest Arterial and Collins Road Northeast. They describe merchandise such as jewelry, shoes, dresses, clothing, and bedding, along with store hours, deals, and directions. This documents a concrete local retail presence, but the sources do not provide evidence about employment, tax benefits, or wider community effects.