
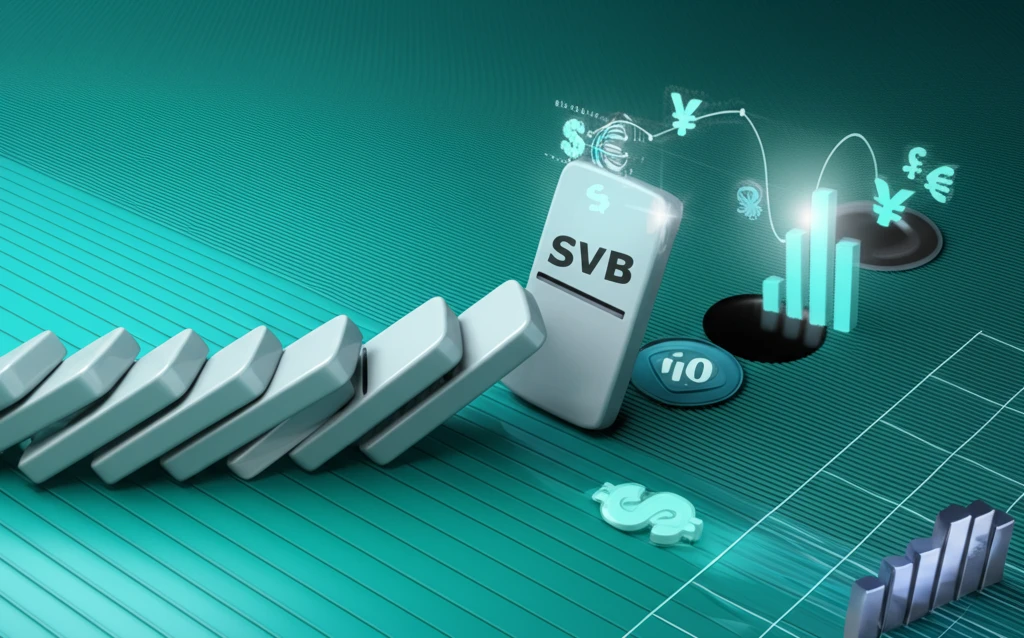
Domino effect symbolizing the SVB failure and its impact on the financial system

Silicon Valley Bank Failure: What Went Wrong and Could It Happen Again?
"A Deep Dive into the SVB Collapse, Contagion Effects, and Lessons for Financial Stability."


The failure of Silicon Valley Bank (SVB) on March 10, 2023, sent shockwaves through the financial world. It was the largest bank failure since the 2008 Global Financial Crisis (GFC), raising concerns about the stability of the entire banking system. SVB's collapse highlighted vulnerabilities that had been building for years, exacerbated by rising interest rates and a unique depositor base.

In the wake of SVB's failure, policymakers stepped in to guarantee all deposits, insured and uninsured, and introduced new lending facilities to shore up confidence. However, the episode underscored the importance of understanding the factors that contributed to SVB's demise and the potential for contagion to other institutions. Financial contagion can spread through interconnected banking networks, information spillovers, and disorderly liquidation of assets. Identifying the specific vulnerabilities that make banks susceptible to contagion is crucial for maintaining financial stability.

This article delves into the key factors that led to the SVB collapse. It examines how interest rate risk, unrealized losses on securities, the nature of SVB's deposits, and regulatory changes created a perfect storm for the bank's failure. By analyzing the contagion effects and identifying the characteristics of banks that were most affected, we can gain valuable insights into the underlying mechanisms driving systemic risk and inform future policy decisions.

AI Search Multiple angles on this topic

Silicon’s Material Importance

Silicon is the eighth most common element in the universe by mass and is widely distributed in cosmic dust, planetoids, and planets. On Earth, it rarely occurs in pure form and is instead found mainly as silicon dioxide or silicates. Silicon has atomic number 14, symbol Si, and functions as a semiconductor used in silicon-based transistors and integrated-circuit chips.

Methodological Limits

A careful analysis of a complex subject generally depends on clearly defined evidence, consistent methods, and transparent treatment of uncertainty. Without subsection-specific source material, no particular accepted method or limitation can be established here. Conclusions should therefore be treated as provisional rather than as settled findings.

Silicon’s Basic Profile

Silicon is described as a hard, brittle crystalline solid with a blue-gray metallic luster. It has the chemical symbol Si and atomic number 14. Compared with neighboring elements in the periodic table, silicon is relatively unreactive and has very high melting and boiling points.

What Were the Main Causes of the SVB Collapse?

Domino effect symbolizing the SVB failure and its impact on the financial system

Several factors converged to trigger the rapid downfall of Silicon Valley Bank. Understanding these elements is critical to grasping the full scope of the crisis:

Interest Rate Risk and Unrealized Losses: SVB had invested heavily in long-term government bonds, which are typically considered safe investments. However, as the Federal Reserve began raising interest rates in March 2022 to combat inflation, the value of these bonds declined. Because SVB held a significant portion of these bonds in its "held-to-maturity" (HTM) portfolio, it didn't have to immediately recognize these losses on its balance sheet. However, the unrealized losses were substantial and became a major concern.

  • Heavy Reliance on Uninsured Deposits: Unlike traditional retail banks, SVB catered primarily to tech startups and venture capital firms. As a result, a large percentage of its deposits were uninsured, meaning they exceeded the $250,000 limit covered by the Federal Deposit Insurance Corporation (FDIC). This made SVB particularly vulnerable to a bank run if depositors lost confidence.
  • Liquidity Risk: As interest rates rose, tech companies began to withdraw their deposits from SVB to fund their operations. This forced SVB to sell some of its HTM securities at a loss to meet these withdrawals, making losses very real.
  • Regulatory Rollback: In 2018, regulations were eased for mid-sized banks, raising the threshold for systemically important financial institutions from $50 billion to $250 billion in assets. This meant that SVB was no longer subject to the same level of scrutiny and regulatory requirements as larger banks, potentially contributing to a weaker risk management framework.
AI Search Multiple angles on this topic

Research Evidence

No subsection-specific research studies or review findings were provided. A reliable assessment would require current, directly relevant research rather than inference from unrelated material. Any conclusions should consequently remain cautious and subject to further verification.

Unresolved Critiques

No source material was provided to identify particular counterarguments, failures, or disputed claims. It would therefore be inappropriate to attribute a specific criticism or outcome to the subject. Further analysis would need evidence addressing competing explanations and documented shortcomings.

Limits of Comparison

No comparative sources were supplied for this subsection. Without matched cases, datasets, or defined comparison criteria, relative performance or risk cannot be assessed reliably. Any ranking or contrast would therefore be speculative.

Together, these factors created a situation where SVB was highly exposed to interest rate risk, had a large amount of uninsured deposits, and faced increasing liquidity pressures. Once concerns about the bank's solvency began to spread, depositors rushed to withdraw their funds, triggering a classic bank run that ultimately led to SVB's failure.

Lessons Learned and the Path Forward

The Silicon Valley Bank failure serves as a stark reminder of the importance of sound risk management practices, effective regulation, and depositor confidence in the banking system. While policymakers took swift action to contain the immediate crisis, several key lessons emerge. Regulators need to consider and devise ways to account for interest rate risk in bank portfolios, particularly the potential for unrealized losses on securities. Stress testing should incorporate scenarios that reflect the unique vulnerabilities of different banks, and supervision needs to be tailored to the specific risk profiles of institutions. In particular, they need to watch out for small- and medium-sized banks.

AI Search Multiple angles on this topic

Cautious Synthesis

The available material does not include expert commentary on the article’s central subject. A sound synthesis would need to distinguish documented evidence from interpretation and acknowledge unresolved uncertainty. On the supplied record, only a limited and provisional conclusion is possible.

Future Assessment

No source-specific projections or future developments were provided. Forecasts about emerging risks, opportunities, or research directions would therefore require additional evidence. Any outlook should be presented as uncertain rather than as a prediction supported by the supplied material.

Systemic Context

The supplied sources do not address broader institutional, economic, or systemic challenges related to the article’s subject. Those issues cannot be characterized responsibly without relevant evidence. Additional sources would be needed to connect individual events with wider structural conditions.

Human Consequences

No subsection-specific sources describe effects on people, organizations, communities, or real-world decision-making. It would therefore be speculative to identify particular human consequences. A complete treatment would require documented accounts or data on affected stakeholders.

How SVB compared with peer banks

SVB’s assets grew much faster than the median for a group of peer banks in 2019–2021; Signature Bank also grew faster than that peer benchmark. The comparison puts SVB’s rapid expansion in context, but does not by itself show what caused the bank’s failure.[1]

Across SVB, Signature Bank, and First Republic, higher uninsured-deposit shares were associated with weaker early stock returns. Their deposit shares were also above the average reported for the comparison set, linking a funding characteristic with market performance rather than establishing cause and effect.[2]

The Federal Reserve’s review described SVB’s managerial weaknesses, concentrated business model, and reliance on uninsured deposits as vulnerabilities that interacted with rising rates and slowing technology-sector activity. That account connects the bank’s exposure to a combination of conditions, rather than to a single trigger.[3]

Growth and liquidity figures in context

  • 198 percent; 134 percent; 33 percent growth in total assetsSVB’s total assets grew 198 percent in 2019–2021, compared with median growth of 33 percent among 19 peer banks. Signature Bank’s growth was 134 percent over the same period.[1]
  • 7 percent; 9.66 percent; 4 percent ratioSVB’s end-of-2019 ratio was 7 percent, below the 9.66 percent average for insured U.S. banks but above the stated 4 percent minimum. The source describes this ratio in the context of liquidity regulation and reserve requirements.[4]

What the SVB evidence leaves open

  • What explains the association between uninsured-deposit shares and early stock returns, and how much does it reflect funding risk rather than other differences among banks?[2]
  • How broadly did large fair-value losses relative to regulatory capital and elevated uninsured funding persist across banks after the regional banking crisis? The Federal Reserve described these vulnerabilities as remaining elevated for a subset, without identifying that subset here.[5]

Words worth knowing about SVB

Reserve requirements
A minimum cash-to-deposits ratio a bank must maintain, with cash held in its vault or at the central bank.[4]

About this Article -

Written with AI assistance from published research, and reviewed by the Mystum team. See our About page for more information.

Everything You Need To Know

1

What was the immediate trigger for Silicon Valley Bank's (SVB) failure, and how did it lead to the bank's collapse?

The immediate trigger for Silicon Valley Bank's failure was a classic bank run. This occurred because depositors, primarily tech startups and venture capital firms, lost confidence in SVB's solvency and rushed to withdraw their funds. This bank run was fueled by rising interest rates, which caused unrealized losses on SVB's bond holdings and raised concerns about the bank's financial health. As SVB had to sell its assets at a loss to meet the withdrawal demands, its financial position further deteriorated leading to the collapse.

2

How did rising interest rates contribute to the downfall of Silicon Valley Bank?

Rising interest rates played a critical role in the failure of Silicon Valley Bank (SVB). SVB had invested heavily in long-term government bonds, which are considered safe, but as the Federal Reserve increased interest rates to combat inflation, the market value of these bonds declined. This resulted in significant unrealized losses on SVB's securities. Furthermore, as interest rates rose, SVB's tech-focused clients began withdrawing deposits to fund their operations, forcing SVB to sell these bonds at a loss to cover the withdrawals, and making losses very real. This combination of factors significantly weakened SVB's financial position and led to a loss of confidence.

3

What role did uninsured deposits play in the Silicon Valley Bank (SVB) failure?

A significant portion of the deposits at Silicon Valley Bank (SVB) were uninsured. Unlike traditional retail banks, SVB catered mainly to tech startups and venture capital firms. Because of this client base, a large percentage of deposits exceeded the $250,000 limit covered by the Federal Deposit Insurance Corporation (FDIC), making them uninsured. This high proportion of uninsured deposits made SVB exceptionally vulnerable to a bank run. When depositors lost confidence in SVB, they quickly withdrew their funds, knowing that their deposits were not fully protected, which triggered the collapse.

4

How did regulatory changes impact the risk profile of Silicon Valley Bank (SVB), and what were the consequences?

Regulatory changes in 2018 played a role in the events leading to the collapse of Silicon Valley Bank (SVB). Specifically, the threshold for systemically important financial institutions was raised, easing regulatory scrutiny for mid-sized banks like SVB. This regulatory rollback meant that SVB was subject to less stringent regulatory requirements than larger banks. This could have contributed to a weaker risk management framework at SVB, making it less prepared for the challenges it faced, such as rising interest rates and deposit outflows, ultimately making the bank more susceptible to failure.

5

What are the key lessons learned from the Silicon Valley Bank failure, and what steps can be taken to prevent similar crises in the future?

The Silicon Valley Bank (SVB) failure highlighted several critical lessons. Sound risk management, effective regulation, and depositor confidence are crucial for financial stability. Regulators need to focus on interest rate risk, particularly the potential for unrealized losses on securities. Stress testing should incorporate scenarios reflecting the unique vulnerabilities of different banks, and supervision should be tailored to the specific risk profiles of institutions. Specifically, regulators should pay close attention to small- and medium-sized banks, as they may pose significant risks to the broader financial system, and consider ways to account for interest rate risk in bank portfolios to prevent future failures.

Newsletter Subscribe

Subscribe to get the latest articles and insights directly in your inbox.