
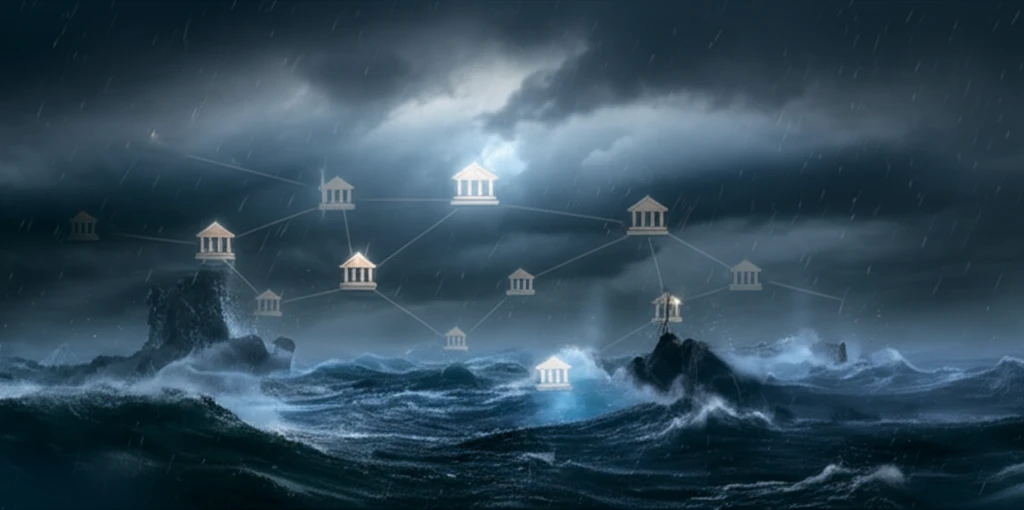
Is Your Bank Safe? Decoding Financial Resilience in a Connected World
"Understanding default resilience and systemic risk in today's complex financial networks."
The global financial crisis of 2007-2008 served as a stark reminder of how interconnected financial institutions can amplify economic shocks. Since then, researchers have been working to understand the vulnerabilities within financial systems, how contagion spreads, and what makes a system resilient.
One area of focus is the structure of financial networks themselves. On one hand, strong connections can help banks share liquidity and support each other during minor crises. However, these same connections can become pathways for shocks to spread rapidly, turning a localized problem into a widespread crisis. This is especially true when institutions share exposures to the same external assets. A sudden drop in the value of a shared asset can impact multiple banks simultaneously, potentially triggering a cascade of defaults.
But how can we measure the risk of such events and protect the financial system? Recent research provides new models for evaluating the 'default resilience' of financial networks and for assessing the potential impact of worst-case scenarios. These models help us understand how much fluctuation a network can withstand and what the consequences might be if those limits are exceeded.
Financial Systems and Resilience
Finance encompasses the management, movement, investment, and raising of money. The field is commonly divided into personal, corporate, and public finance, while the financial system enables assets to be bought, sold, or traded as financial instruments. The listed sources do not provide current bank-safety statistics, so they cannot support a numerical assessment of financial resilience.
Advisor Discovery and Its Limits
A standard consumer approach may begin with searching for financial advisors by location and comparing available listings. Yelp presents a list of the top 10 financial advisors near Greeley, Colorado, marked as updated in 2026 and sorted by recommended results. Such a directory can support initial discovery, but the provided material does not establish how advisor quality, financial strength, or bank safety is evaluated.
A Long-Running Financial Evolution
Financial institutions and markets have developed over time as societies created ways to manage, transfer, invest, and raise money. The specific milestones and foundational discoveries behind that development vary across regions and institutions. Without source material for this subsection, any detailed historical account would require additional evidence.
What is Default Resilience and Why Does It Matter?
Imagine a network of banks, each with connections to others and holdings in various external assets (like stocks or bonds). Now imagine the value of those assets suddenly fluctuating – some going up, others going down. Banks are simultaneously impacted, their balance sheets adjusting. The question then becomes: how much of this fluctuation can the network absorb before some banks start to fail?
- Default Resilience Margin: The maximum amplitude of asset price fluctuations a network can withstand without defaults.
- Worst-Case Systemic Loss: The total unpaid debt if asset prices fluctuate beyond the resilience margin.
- Linear Programming: A mathematical method used to calculate both the resilience margin and worst-case loss.
Evidence in Progress
Recent research on bank safety may examine capital, liquidity, governance, technology, and interconnectedness. Findings can change as new data, regulatory reviews, and market conditions become available. No sources were provided here, so this subsection remains a general framing rather than a summary of specific studies or results.
Limits of Confidence
A bank may appear stable under ordinary conditions yet face pressure when confidence, liquidity, or connected financial relationships change quickly. Resilience claims should therefore be treated cautiously rather than as guarantees of protection in every scenario. No source material was provided to document a particular failure, counterargument, or disputed claim.
Comparing Resilience
Comparing banks generally requires consistent information about their financial condition, risk exposure, safeguards, and operating environment. Differences in regulation, business models, and market connections can affect how meaningful a comparison is. Without subsection-specific sources, no evidence-based ranking or direct comparison can be made.
The Future of Financial Stability Modeling
The models discussed in this research offer valuable tools for understanding and managing risk in financial networks. By quantifying default resilience and assessing potential losses, regulators and institutions can better prepare for economic shocks and protect the stability of the financial system. Future research will likely focus on refining these models, incorporating factors like illiquid assets and the costs associated with defaults and bankruptcies.
A Balanced Assessment
A useful assessment of bank safety should combine institutional information with attention to broader financial connections and changing conditions. Resilience is best understood as a capacity that can be tested, not as an absolute promise. No expert commentary was supplied for this subsection, so these points are deliberately general.
Emerging Challenges
The future of banking may involve deeper digital connectivity, faster transactions, and increasingly complex dependencies among institutions and markets. These developments could create new opportunities while also introducing risks that require continued oversight. The available material does not identify specific technologies, forecasts, or next-frontier research.
The Wider Financial Network
Bank safety exists within a broader financial system rather than in isolation. Problems can potentially spread through shared markets, institutions, infrastructure, or confidence, although the scale and likelihood of such effects depend on circumstances. No sources were provided to support a specific systemic-risk example or measurement.
Accessible Financial Information
Google Finance provides real-time market quotes, international stock information, financial news, currency conversion rates, and tracking tools. These features can help people monitor financial developments and make information more accessible in a connected world. The source does not establish that the service evaluates bank safety or provides personalized financial advice.