
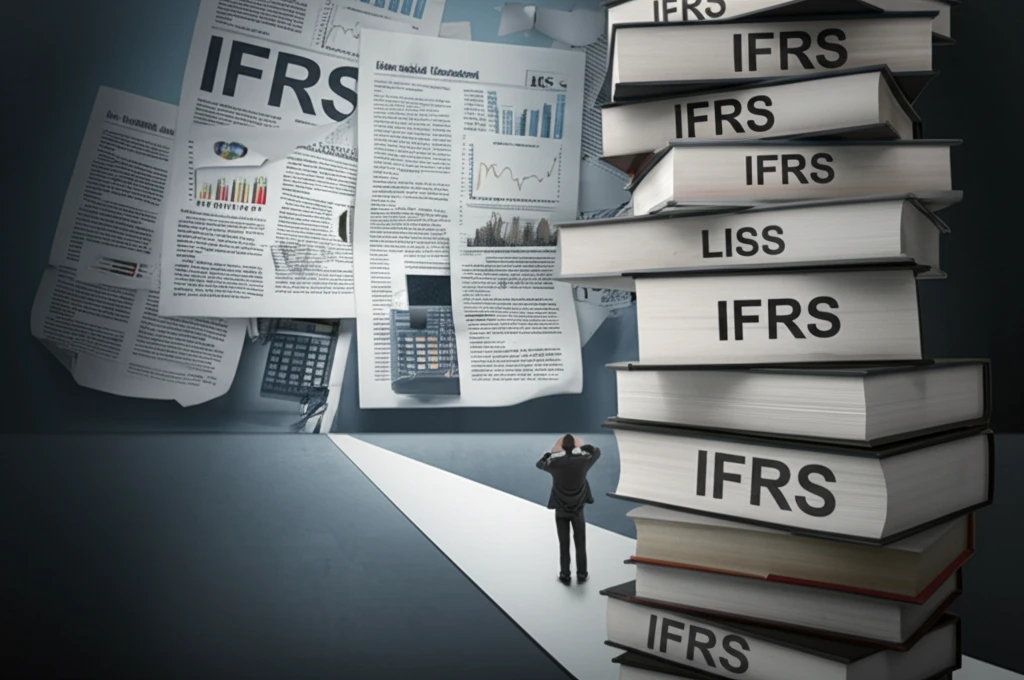
Small Business Accounting: Are IFRS Standards Overcomplicating Things?
"Discover how International Financial Reporting Standards (IFRS) might be creating unnecessary complexity for small and medium-sized businesses, impacting their financial reporting and overall operations."
For many small and medium-sized enterprises (SMEs), the world of financial reporting can feel like navigating a maze. International Financial Reporting Standards (IFRS), designed to bring uniformity and transparency to financial statements, often seem overwhelming. While these standards aim to ensure that financial information is reliable and comparable across different companies and countries, their complexity can pose significant challenges for smaller businesses.
Introduced to enhance the quality of financial reporting, IFRS standards require a detailed understanding of accounting principles and meticulous record-keeping. However, SMEs often operate with limited resources, including fewer staff members and less financial expertise. This scarcity of resources means that adhering to IFRS can divert attention from core business activities, leading to inefficiencies and increased operational costs.
This article examines the issues surrounding IFRS for SMEs, particularly focusing on whether these standards are excessively complicated for smaller businesses. By delving into the experiences of South African small company practitioners, we aim to uncover the practical difficulties encountered and explore potential solutions for a more streamlined and effective financial reporting process. Are IFRS standards truly serving the best interests of SMEs, or is a simpler, more tailored approach needed?
Defining Small in Business Contexts
The term 'small' in business contexts lacks universal definition, with dictionary references characterizing it as having comparatively little size or slight dimensions. While 'Small' also refers to prominent nanoscience and nanotechnology journals covering research at nano and microscales, these sources do not provide specific statistics on small business accounting challenges. The ambiguity in defining 'small' enterprises complicates efforts to assess the impact of complex accounting standards like IFRS on smaller entities. Different regulatory bodies and industries often apply varying thresholds for what constitutes a small business, creating inconsistency in research and policy discussions.
Generally Accepted Accounting Principles
Most small businesses rely on simplified accounting frameworks rather than comprehensive international standards, though specific data on adoption rates remains limited. Small entities often face practical challenges when attempting to comply with complex regulatory requirements, including resource constraints and limited accounting expertise. The tension between standardization goals and practical implementation challenges represents an ongoing area of discussion among practitioners and regulators. Without empirical evidence, it is difficult to assess whether current approaches adequately serve the needs of diverse small business operations.
Evolution of Accounting Terminology
The concept of 'small' in business has evolved alongside broader economic and linguistic developments, though detailed historical analysis of accounting standards for small entities is sparse. Historical records and thesaurus references show that words like 'small,' 'little,' and 'diminutive' have long been used to describe entities of lesser scale, with numerous synonyms including tiny, miniature, and slight. The formalization of accounting standards for small businesses is a relatively recent phenomenon compared to standards developed for larger enterprises. Foundational discoveries in accounting theory have traditionally focused on publicly traded companies, leaving smaller entities with adapted rather than purpose-built frameworks.
Why Are IFRS Standards a Challenge for Small Businesses?
The comprehensive nature of IFRS can be a double-edged sword. While thoroughness is essential for accuracy, the level of detail required can be burdensome for SMEs. Many small businesses find that the extensive disclosure requirements and complex technical calculations demand significant time and expertise, straining their already limited resources. This situation raises a critical question: are the benefits of full IFRS compliance justified for smaller entities, or do the costs outweigh the advantages?
- Limited Resources: SMEs typically have fewer staff members and less financial expertise compared to larger corporations. This scarcity of resources makes it challenging to allocate sufficient time and effort to IFRS compliance.
- High Compliance Costs: Adhering to IFRS can incur substantial additional costs, including the need for specialized accounting software, external consultants, and ongoing training for staff.
- Complexity of Standards: IFRS standards often involve intricate technical calculations and extensive disclosure requirements, demanding a high level of accounting expertise that may not be readily available within small companies.
- Unique Financial Burdens: The costs associated with IFRS compliance can create a unique financial burden for small companies, potentially exceeding the benefits gained from supplying the correct information.
Current Research Landscape
Recent literature on small business accounting standards remains fragmented, with limited large-scale studies examining IFRS compliance burdens specifically for small enterprises. Some researchers have explored simplified reporting frameworks as alternatives to full standard compliance, though consensus on optimal approaches has not yet emerged. The intersection of technology adoption and accounting compliance presents emerging research opportunities that could inform future policy decisions. Without comprehensive recent reviews, definitive conclusions about the current state of small business accounting standards require further investigation.
Alternative Perspectives
Critics of simplified accounting approaches argue that reduced standards may compromise financial transparency and stakeholder confidence, though empirical evidence of failures remains limited. Some practitioners contend that complexity in standards serves important regulatory purposes even for small entities, challenging the premise that simplification is universally beneficial. Documented cases of accounting failures in small businesses are difficult to attribute specifically to standards complexity rather than other factors like management practices or economic conditions. The counter-argument that standardization promotes comparability and investor confidence has theoretical merit but requires empirical validation in small business contexts.
Differing Regulatory Approaches
Comparative analysis of international approaches to small business accounting reveals significant variation in regulatory frameworks across jurisdictions. Some countries have implemented tiered systems with reduced requirements for smaller entities, while others apply more uniform standards regardless of entity size. The effectiveness of different approaches in balancing compliance burden with reporting quality has not been conclusively established through rigorous comparative studies. Cultural, economic, and institutional differences between countries complicate direct comparisons of accounting standard outcomes for small businesses.
Simplifying Accounting for Small Businesses: A Path Forward
The journey toward simplifying accounting for small businesses requires a collaborative effort. Regulatory bodies, accounting professionals, and small business owners must work together to develop standards that are both effective and practical. By focusing on relevance, reducing complexity, and providing adequate support, we can ensure that IFRS for SMEs truly serves its intended purpose: to promote transparency and facilitate informed decision-making without overburdening the businesses that drive our economies.
Integrating Multiple Perspectives
Expert commentary on small business accounting standards generally acknowledges the tension between standardization goals and practical implementation challenges. Synthesis of available evidence suggests that context-specific solutions may be more appropriate than universal approaches, though this view remains contested among standard-setters. The lack of comprehensive, high-quality research limits the ability to form definitive conclusions about optimal approaches. Future expert analysis would benefit from more robust empirical data to move beyond theoretical arguments.
Emerging Trends and Developments
Future developments in small business accounting may be shaped by technological innovations that could reduce compliance burdens through automation and simplified reporting tools. Emerging digital infrastructure and cloud-based accounting platforms present opportunities to reimagine how standards are implemented in practice. The potential for AI-assisted compliance monitoring could fundamentally change the cost-benefit analysis of complex standards for small entities. However, predictions about technological solutions should be tempered by recognition that adoption barriers and digital divides may persist.
Systemic Considerations
Small business accounting standards exist within broader systemic challenges including regulatory harmonization efforts and competing stakeholder interests. The tension between national sovereignty in standard-setting and international convergence goals creates ongoing friction that affects small entities disproportionately. Resource allocation decisions by standard-setters inevitably prioritize some stakeholder groups over others, with small businesses often having less representation in policy discussions. Systemic solutions require coordinated action across multiple institutional levels that has proven difficult to achieve historically.
Practical Implications for Business Owners
For small business owners and managers, accounting standards complexity translates into tangible costs including time, money, and cognitive burden that could otherwise be directed toward core business activities. The practical experience of implementing complex standards varies significantly based on available resources, industry context, and individual capabilities. Anecdotal reports suggest frustration with compliance requirements that seem disproportionate to the reporting benefits for smaller entities, though systematic data on these experiences is limited. Understanding the human element requires acknowledging that accounting standards exist to serve real people and businesses, not merely abstract regulatory goals.