
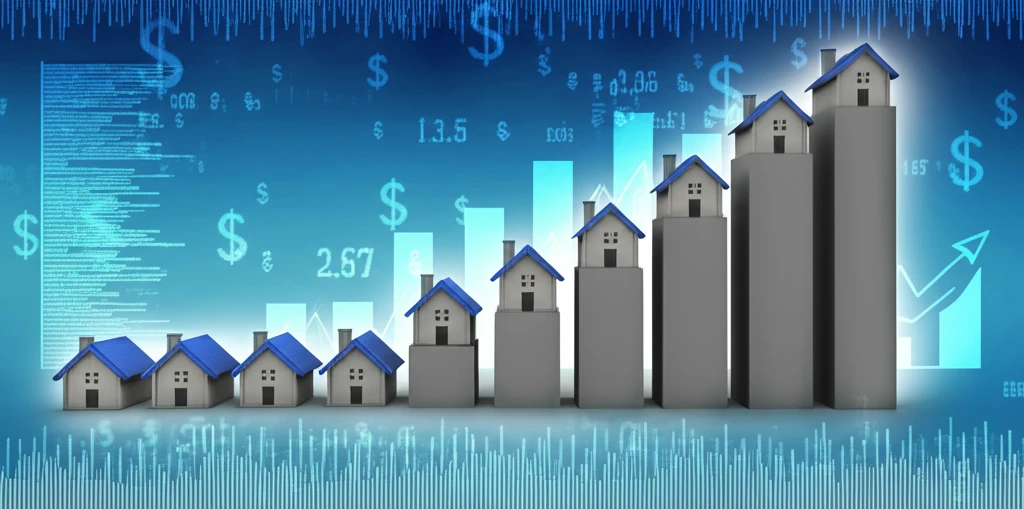
Decoding the Housing Market: What House Prices and Indices Tell Us About Income
"Dive into the surprising connection between housing market trends and income distribution, uncovering key insights for homeowners and investors alike."
Ever wondered what the fluctuations in house prices really signify? Beyond the typical buying and selling, the housing market offers a unique lens through which we can view the broader economic landscape. Specifically, the distribution of house prices and the trends in house price indices (HPI) can reveal surprising insights into income distribution within a community.
Traditionally, analyzing income distribution has been challenging due to data limitations. However, by treating house prices as a 'derivative' of income, and HPI as its second derivative, we gain a more detailed and nuanced understanding. This approach allows us to examine economic patterns using data that's both readily available and closely tied to personal wealth.
Recent research leverages this concept, analyzing data from over 116,000 single-family homes in Hamilton County, Ohio, alongside HPI data from nearly 18,000 US ZIP codes. The aim? To uncover patterns, outliers, and potential indicators of economic behaviors, like 'Dragon Kings'—extreme events that significantly skew distributions. Understanding these patterns is essential for homeowners, investors, and anyone keen on grasping the underlying forces shaping our economy.
Affordability Benchmarks in Olympia and Thurston County
In Olympia, Washington, housing affordability is formally defined against local income: a project qualifies as low-income housing when it serves households earning at or below 80% of the area median income. Listing services such as Zillow currently advertise hundreds of rental units across the city, but eligibility for assisted housing still turns on that income benchmark rather than on advertised prices alone. For lower-income and at-risk residents, assistance is channeled through the Housing Authority of Thurston County, with emergency and transitional housing applications coordinated through the county's Coordinated Entry system. The agency's stated mission of providing safe, decent, and affordable housing to persons with disabilities, low-income, and at-risk individuals shows how official indices and local eligibility rules shape who can actually access housing.
Listing Aggregators as a Proxy for Affordability
Rental platforms like Apartments.com represent a standard, widely used approach to judging housing affordability: aggregating listings and letting users filter by neighborhood and rent. The site's Olympia coverage highlights budget-friendly neighborhoods such as Colonial Estates, South Westside, and Downtown Olympia, an implicit acknowledgment that affordability varies sharply within a single market. The limitation of this approach is that advertised asking rents and curated neighborhood tags are proxies rather than true affordability measures, since they say nothing directly about household income, eligibility rules, or cost-burden thresholds. As a result, such methods are useful starting points but cannot substitute for income-indexed measures like those used by local housing authorities.
A General View of Housing and Income Indexing
No authoritative published history of housing price and income indexing is covered by the available sources, so only a general narrative can be offered here. For decades, home price indices have tracked how property values change over time, while affordability metrics typically compare prices against median household incomes. Early index construction relied on relatively coarse data, and later refinements aimed to correct for changes in the mix of homes sold. Any specific milestone or founding study in this area should be verified against original source documents before being treated as established fact.
House Prices as a Window into Economic Trends
Imagine the housing market as a giant thermometer, gauging the financial health of a community. Each sale, each price increase, and each market trend reflects the collective economic activity and income distribution. By analyzing the data points, like sale prices and HPI, economists can piece together a detailed picture of who’s earning what, and how wealth is spread across different areas.
- House Prices (HP): Think of these as a snapshot of individual financial health. A higher house price often reflects higher income and purchasing power. By mapping the distribution of house prices, you can visualize the income landscape of a region.
- House Price Indices (HPI): These indices track the change in house prices over time. If house prices in one area are consistently rising faster than in another, it could indicate growing income inequality or different rates of economic growth.
- Generalized Beta (GB) Distributions: Advanced statistical models, like the GB family of functions, help economists fit these distributions to real-world data, revealing nuances like 'fat tails' (indicating high inequality) or 'Dragon Kings' (extreme outliers).
The Rapidly Shifting Research Landscape
Current research on the relationship between house prices and household income is evolving rapidly, but much of the most recent work appears in proprietary analytics and subscription research rather than open academic outlets. Methodologies now range from simple price-to-income ratios to repeat-sales indices and hedonic models that adjust for property characteristics. Because underlying data sources and definitions vary, recent findings are best treated as provisional and should be checked against the primary studies on which they rely. At a general level, researchers consistently report that home prices have risen faster than incomes in many markets, though the magnitude remains debated.
Why Simple Ratios Face Criticism
A common counterargument holds that simple affordability ratios, such as median price divided by median income, are misleading because they ignore interest rates, down payments, and the mix of properties sold. Critics point out that aggregate indices can overstate or understate affordability problems when neighborhoods differ sharply and supply constraints push up prices in some segments only. Past weaknesses of single-metric approaches, such as relying solely on listed asking prices or unadjusted medians, have led to calls for more nuanced, income-indexed measures. Without consensus data, these debates are best summarized as a broad critique rather than attributed to specific documented failures.
Comparing Markets on Common Ground
Comparing cities or regions on housing affordability typically requires parallel price and income data, which are not consistently available for all markets. Some analysts compare price-to-income ratios, others use rent-to-income or cost-burden statistics, and the resulting rankings can diverge considerably depending on the measure chosen. A rough generalization is that high-employment, high-demand areas generally show weaker price-to-income ratios than the national average, while lower-cost regions remain more affordable. Because underlying datasets differ, such comparisons should be read as indicative rather than definitive.
The Future of Housing Market Analysis
The insights gleaned from analyzing house prices and indices offer just a glimpse into the potential of this approach. As data becomes more accessible and analytical tools more sophisticated, expect to see even deeper connections uncovered between the housing market and broader economic trends. Whether you're a homeowner, investor, or policy maker, understanding these relationships is crucial for making informed decisions and navigating the ever-changing economic landscape.
Two Measures, One Affordability Story
Without attributable primary sources on this topic, expert commentary must be presented cautiously. A reasonable synthesis is that price indices and income statistics answer different questions, what housing costs versus who can pay for it, and each is incomplete on its own. Analysts generally agree that pairing the two reveals affordability gaps that either metric alone would obscure. Specific expert verdicts, however, should be verified against original publications before being treated as settled.
Data-Backed Analytics Drive the Next Phase
Market participants increasingly look to institutionally produced, data-backed analytics to anticipate where housing prices and affordability are headed. Bank of America, through its Institute research offering, positions itself as a source of deep analysis and insights rooted in the expertise of industry-leading analysts, with an emphasis on broader economic trends. Such resources signal a shift toward continuous, data-driven monitoring of housing and income dynamics rather than one-off reports. The outlook implied by this shift is that sophisticated, subscription-style analytics will play a growing role in interpreting how price indices interact with household income.
Structural Forces Beyond the Index
Viewed broadly, housing affordability is entangled with structural forces such as local zoning, construction costs, land constraints, and income distribution that lie beyond any single index. Systemic challenges arise because price signals and income data are gathered by different agencies using different cutoffs and time horizons, complicating direct comparison. Policy responses likewise vary, with some jurisdictions relying on market-based signals and others on income-defined eligibility thresholds. A full account of these systemic issues would require authoritative multi-jurisdiction data that is not currently covered by the sources available here.
Statistics With a Human Face
Behind the indices, housing affordability is ultimately a human story about households' ability to secure stable shelter without sacrificing other necessities. Families, seniors, and residents with disabilities navigating limited affordable options underscore the real-world stakes of seemingly abstract statistics. Because this subsection had no dedicated source material, the human impact is described here only in general terms rather than through documented cases. Readers should turn to local housing authority reporting and community surveys for concrete, real-world accounts.