
Decoding the Hidden Risks: How to Protect Yourself from Information Asymmetry in Everyday Life
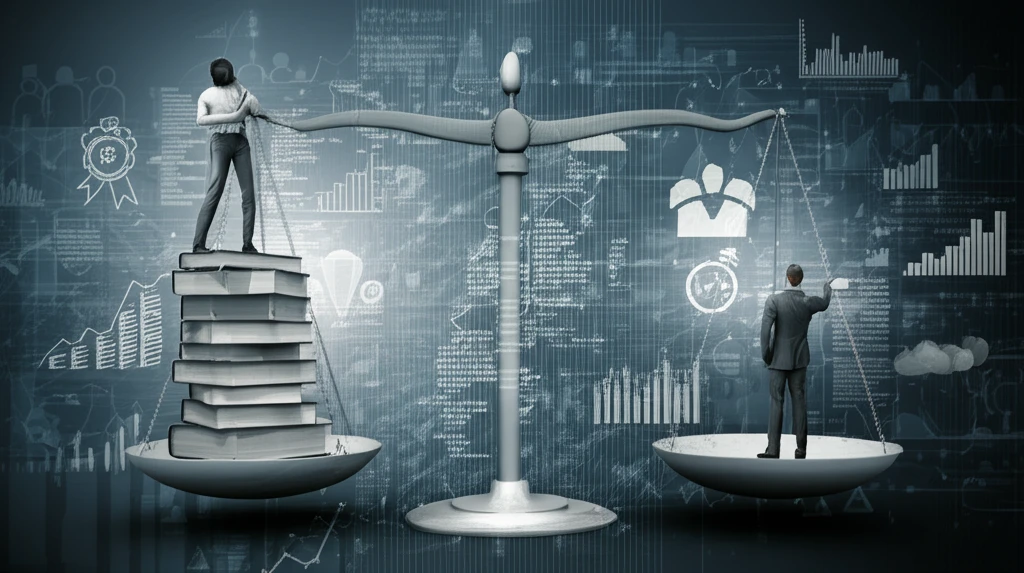
"Navigate the murky waters of unequal knowledge: A straightforward guide to spotting and mitigating information asymmetry in insurance, job markets, and beyond."
In a world buzzing with data, it's easy to assume everyone has access to the same information. But what happens when one party in a transaction knows significantly more than the other? This imbalance, known as asymmetric information, isn't just an academic concept; it's a real-world force that shapes our decisions and impacts our wallets.
Imagine buying a used car, choosing a health insurance plan, or even accepting a new job. In each scenario, someone likely holds more knowledge than you do—the seller knows the car's hidden problems, the insurance company understands the fine print, and the employer is aware of the company's challenges. This information gap can lead to unfair deals, poor choices, and a general feeling of being at a disadvantage.
This article dives deep into the world of asymmetric information, drawing from extensive research to explain how it manifests in various aspects of life. More importantly, we'll equip you with practical strategies to recognize these imbalances and protect yourself from their potentially harmful consequences.
The Scale of Information Asymmetry
Information asymmetry remains a pervasive challenge across economic markets, manifesting primarily through adverse selection and moral hazard. According to recent research, these two phenomena are central manifestations that distort the efficiency of insurance and financial markets. Moral hazard occurs when a party insulated from risk has more information about its actions than the party bearing the negative consequences. Adverse selection arises when one party's private information before contract signing creates market imbalances, particularly in insurance and lending contexts.
Traditional Approaches to Addressing Asymmetry
Economists have developed several standard approaches to mitigate information asymmetry, including screening mechanisms, signaling strategies, and regulatory interventions. Screening involves the less-informed party designing mechanisms to induce the more-informed party to reveal private information. Signaling occurs when the informed party takes costly actions to credibly convey information. However, these methods have limitations: they can be costly to implement, may not fully eliminate information gaps, and sometimes create new forms of market distortion.
Evolution of Asymmetric Information Theory
The formal study of information asymmetry emerged in the 1960s and 1970s through the work of economists like George Akerlof, Michael Spence, and Joseph Stiglitz. Akerlof's famous 'Market for Lemons' paper demonstrated how adverse selection could cause market failure in used car markets. Spence's job market signaling model showed how education could serve as a credible signal of productivity. These foundational contributions, which earned Nobel Prizes in Economics, established the theoretical framework for understanding how information gaps affect market efficiency and economic outcomes.
Understanding Asymmetric Information: The Core Problems
At its heart, asymmetric information boils down to unequal access to relevant facts. This inequality breeds several problems, most notably moral hazard and adverse selection. Understanding these concepts is crucial for navigating information-skewed situations.
- Insurance premiums rise: Insurers try to account for potential moral hazard by raising premiums for everyone.
- Reduced services: Insurers might limit coverage or increase deductibles to discourage risky behavior.
- Distorted markets: The overall efficiency of the insurance market suffers as a result of these adjustments.
Contemporary Understanding of Information Gaps
Recent scholarship continues to refine our understanding of information asymmetry's mechanisms and consequences. Researchers are exploring how digital technologies and big data analytics create new forms of information advantage and disadvantage. The interplay between adverse selection and moral hazard remains a central focus, with studies examining how these phenomena interact in complex markets. Modern analysis increasingly recognizes that information asymmetry is not just an economic problem but a systemic challenge affecting healthcare, education, and public policy domains.
Challenges to Information Asymmetry Theory
While information asymmetry theory provides valuable insights, some scholars argue it oversimplifies market dynamics. Critics point out that markets often develop informal mechanisms to address information gaps without formal intervention. Behavioral economics research suggests that bounded rationality and cognitive biases complicate the clean theoretical models of asymmetric information. Additionally, some empirical studies find that information advantages do not always translate into expected economic outcomes, challenging the predictive power of traditional models.
Adverse Selection vs. Moral Hazard in Financial Systems
Information asymmetry creates two distinct problems in financial markets: adverse selection and moral hazard. Adverse selection explains why banks dominate corporate lending, why collateral is standard practice, and why financial systems require heavy regulation. In insurance markets, adverse selection occurs when high-risk individuals disproportionately seek coverage, destabilizing risk pools. Moral hazard, by contrast, happens after transactions occur when protected parties take excessive risks because they don't bear the full consequences of their actions.
Leveling the Playing Field: Practical Steps for Protection
While asymmetric information is a pervasive challenge, it's not insurmountable. By being proactive and informed, you can mitigate its negative effects and make better decisions. The key is to recognize situations where information imbalances exist and take steps to bridge the gap. Ask questions, seek expert advice, compare prices, and always read the fine print. Your diligence will empower you to navigate these tricky situations with confidence and secure the best possible outcomes. Remain vigilant and embrace a healthy dose of skepticism, and you will empower yourself to make sound decisions in an imperfect world.
Expert Perspectives on Information Asymmetry
Academic experts distinguish between two primary models of information asymmetry. In hidden action or moral hazard models, an agent's choices affect a principal, but the principal cannot directly observe those actions. In hidden type or adverse selection models, an agent's private information remains unknown until after contract signing. This distinction is crucial for designing effective interventions, as the solutions for hidden action problems differ fundamentally from those addressing hidden type problems.
Emerging Frontiers in Information Economics
The future of information asymmetry research lies in understanding how technological advances reshape traditional information gaps. Artificial intelligence and machine learning may both reduce certain information asymmetries through better data analysis and create new ones through algorithmic complexity. Blockchain and decentralized technologies offer potential solutions for transparency but also introduce new forms of information advantage. The intersection of behavioral economics with information theory promises more nuanced models of how humans process and act on asymmetric information in real-world decision-making contexts.
Systemic Implications of Information Gaps
Information asymmetry presents significant challenges to market efficiency and stability across economic systems. Adverse selection creates opportunities for exploitation by those with superior information, while moral hazard leads to excessive risk-taking due to protection from consequences. These phenomena are particularly problematic in insurance and financial markets, where they can destabilize risk pools and distort resource allocation. The persistence of information asymmetry suggests that markets alone cannot achieve optimal outcomes without some form of intervention or institutional design.
Practical Consequences of Information Asymmetry
Information asymmetry has tangible real-world consequences in everyday transactions. In used car markets, sellers typically have more information about vehicle quality than buyers, leading to adverse selection where low-quality vehicles dominate. Insurance markets face similar challenges when applicants know their true risk levels better than insurers. Government interventions such as disclosure requirements, warranties, and regulatory oversight attempt to mitigate these information imbalances, though they introduce their own costs and complexities to market functioning.