
Decoding Financial Markets: How Hierarchical Causality Shapes the Economy
"Uncover the hidden forces driving market behavior and learn how multi-level interactions impact your financial decisions."
Financial markets are complex systems, driven by a multitude of interacting factors and prone to unpredictable events. The 2008 financial crisis highlighted the limitations of traditional economic models in capturing this complexity. Understanding the various layers of influence, from individual investors to global regulatory bodies, is crucial for navigating today's economic landscape.
The concept of 'hierarchical causality' offers a valuable framework for analyzing these intricate systems. Instead of focusing solely on cause-and-effect relationships, this approach acknowledges that causality operates at multiple levels, with each level influencing and being influenced by others. This perspective moves beyond simplistic reductionist views, embracing a more holistic understanding of market dynamics.
This article delves into the concept of hierarchical causality in financial economics. We will break down the different levels of influence, from the actions of individual agents to the impact of ethical considerations, revealing how these interconnected forces shape market behavior. Whether you're an investor, a student, or simply curious about the forces that drive the economy, this exploration will offer valuable insights into the complexities of the financial world.
A Growing Field Built on Data and Time-Series Evidence
Research on causality in financial markets is extensive and expanding. A time-varying Granger causality study of the United States over the 1960-2021 period reports bidirectional causality between the stock market and macroeconomic fundamentals, while a separate analysis of the German DAX and the U.S. Dow-Jones index separates linear from nonlinear causal contributions using Fourier transform surrogates. Large-scale resources support this line of inquiry: the FinSen dataset integrates economic and financial news from 197 countries with stock market data, spanning 2007 to 2023 and containing roughly 160,000 records with temporal information. Publication tracking from the Nature Index shows a rising annual volume of articles in financial market dynamics and volatility analysis, underscoring the field's sustained footprint.
The Standard Toolkit and Where It Falls Short
Conventional approaches to financial causality typically rely on time-series methods such as Granger causality, which test whether past values of one series help predict another. These methods are widely used because they are transparent and computationally tractable, but they carry well-known limitations, including sensitivity to variable selection, lag specifications, and underlying assumptions about linearity and stationarity. Statistical association detected by such tests does not by itself establish a true causal mechanism, and it may overlook nonlinear or time-varying relationships that matter in real markets. As a result, findings are generally best interpreted as evidence about predictive structure rather than definitive causal proof.
Four Centuries of Market Evolution
Financial markets have been shaping the global economy for roughly four centuries, and observers note that the stock market effectively records this history, capturing the financial and economic revolutions that drove change in the world. In London, the Royal Exchange contributed to the city's rise as a global financial center by facilitating not only trade but also the exchange of information and ideas among merchants, laying the groundwork for modern commodities markets. Historical case studies of significant market events and empirical analyses of market data help provide insight into how these markets function and evolve across eras. Comprehensive treatments of the topic typically organize this record around key concepts, mathematical models, and methodologies used to study market dynamics.
Understanding the Levels of Influence in Financial Markets
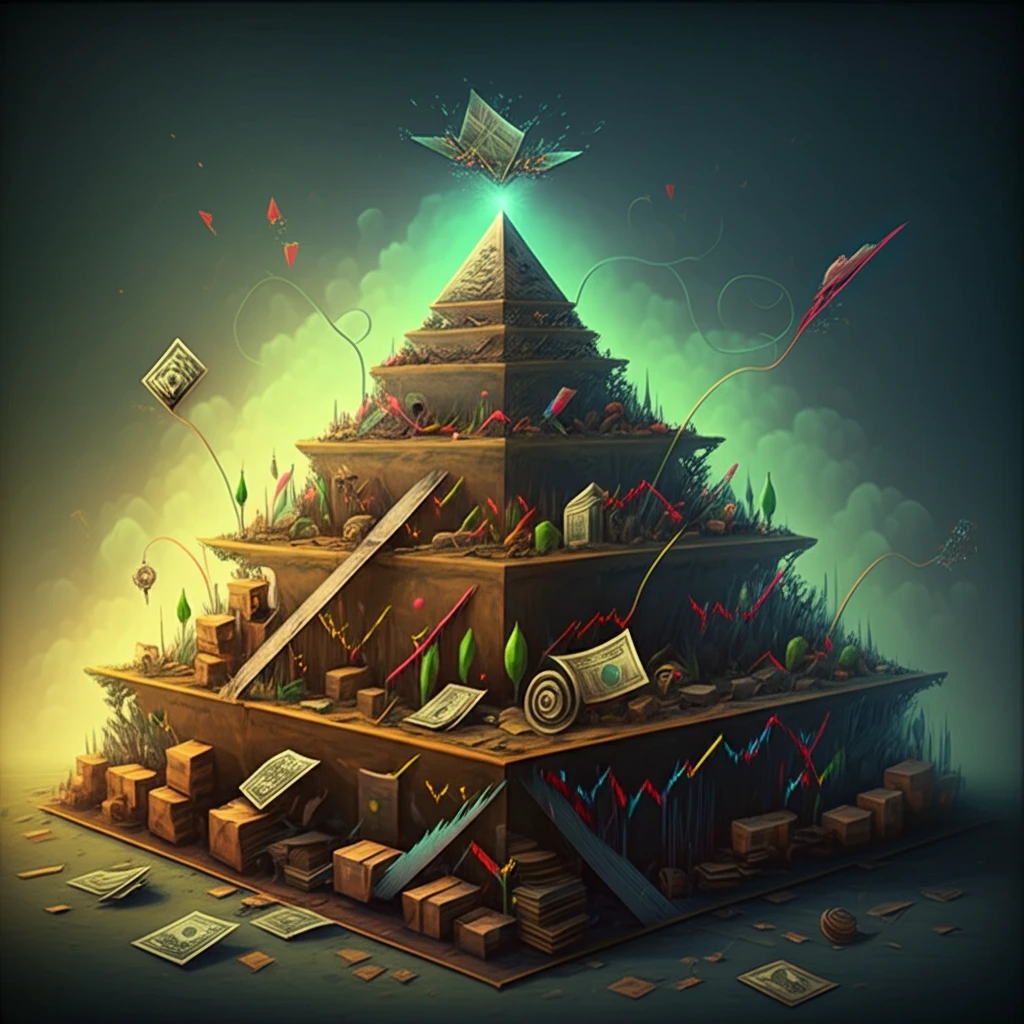
To grasp the concept of hierarchical causality, it's helpful to visualize the financial market as a multi-layered structure. Each layer represents a distinct level of interaction, with its own set of actors, rules, and dynamics. The actions at each level ripple through the system, influencing and being influenced by other levels. Understanding the key players and dynamics at each stage makes sense of the chaos. Hierarchical causality is complex in finance, due to global relations with no single source of truth. As a result, models have to adopt for new states and parameters.
- Individual Agents: At the base of the hierarchy are the individual agents – the investors, traders, and institutions that buy and sell assets. Their decisions, driven by individual motivations and information, generate the prices of individual assets.
- Market Aggregation: The next level involves the aggregation of individual stocks into broader markets. This level reflects the collective behavior of agents and the interactions between different assets.
- Risk Factors and Information: This level combines shared risk factors, which affect multiple assets simultaneously, with the flow of information. This interaction determines market-wide trends and pricing patterns. No arbitrage pricing theory are formed, that describes efficient markets with no risk to investors. This may not form for various reasons.
- Economic Factors: The broader economy exerts its influence at this level, with factors like interest rates, inflation, and economic growth impacting market sentiment and investment decisions.
- Regulatory Structure and Ethics: The highest level encompasses the regulatory framework and the ethical considerations that govern market behavior. These factors define acceptable transactions, set boundaries for market conduct, and influence overall market stability.
From Univariate Tests to Global Networks
Latest research has moved beyond single-market tests toward multivariate frameworks that map causal connections across regions. One recent study examines the interconnectedness of global financial markets using a multivariate Granger causality framework focusing on the United States, Europe, Asia, and emerging markets, motivated by the observation that traditional linear models often fail to capture inherent nonlinearities between markets. In parallel, scholars are probing the limits of conventional models altogether, including work on reflexivity in capital markets that examines how causal ambiguity arises when systems are self-referential and unidirectional causal chains are assumed. Complementary work on linear and nonlinear causality indicates a significant shift in how financial market behavior is perceived and quantified, with insights promising refined market predictions, optimized trading strategies, and improved portfolio risk management.
When Statistical Causality Falls Short
A recurring critique is that purely statistical approaches to financial causality have critical limitations, because patterns detected in data do not automatically align with genuine economic mechanisms. Recent work such as the FinCARE framework argues for grounding statistical discoveries in financial domain expertise while maintaining empirical validation, giving portfolio managers a causal foundation for proactive risk management. Complicating matters further, empirical evidence indicates that the relationship between the financial sector and the real economy is not neatly one-directional: Granger-causality tests support a robust bidirectional causality between financial and real difficulties, with the financial sector influencing the real economy more significantly. These critiques suggest that progress depends on combining data-driven inference with institutional knowledge rather than relying on either alone.
Linear Versus Nonlinear Causal Inference
Comparative research in this area centers on how causality is identified, with a key distinction drawn between linear and nonlinear contributions. One line of work presents a more general framework for assessing co-dependencies by identifying both linear and nonlinear causalities within the complex system of financial markets. The same body of research suggests that nonlinear causality can be a valuable tool for anticipating and evaluating financial impacts, provided it is continually monitored and assessed in the context of evolving market dynamics. This comparative lens matters because it changes both how closely markets can be measured and how their behavior is interpreted over time.
Embracing Complexity for Better Understanding
The financial market is a complex adaptive system, influenced by multiple interacting forces. By understanding the different levels of causality and their interconnections, we can develop a more nuanced and realistic view of market behavior. This understanding can empower investors to make more informed decisions, policymakers to design more effective regulations, and researchers to develop more robust economic models.
Where the Evidence Converges
Taken together, the literature suggests that financial causality is real but rarely simple or unidirectional. Studies point to meaningful predictive relationships between markets and macroeconomic fundamentals, while also emphasizing that these relationships vary over time, involve both linear and nonlinear components, and can run in both directions. The most credible picture is one of dynamic interdependence rather than stable cause-and-effect chains. Expert commentary accordingly tends to frame causal analysis as a continuously updated diagnostic rather than a one-time finding.
Toward Richer Causal Accounts
Looking ahead, researchers are likely to push beyond single-method tests toward frameworks that combine multiple causal techniques, larger and more diverse datasets, and structured domain knowledge. Expect greater attention to time-varying and nonlinear relationships, and to how reflexive or feedback-driven dynamics distort conventional inference. Better data coverage and computational methods may allow causal maps that span many markets and regions simultaneously. These developments, if they mature, could meaningfully support forecasting, portfolio risk management, and policy decisions, though their practical payoff remains to be demonstrated.
Crisis Dynamics and Systemic Risk
Financial crises rarely have a single cause, and recent analysis underscores how multiple mechanisms combine in practice. The impact of the 2008 financial crisis was likely driven in part by panics and in part by balance-sheet effects: panics within the shadow banking system froze some credit markets and negatively affected financial institutions that financed their operations through uninsured short-term liabilities. Crisis research also highlights the tricky question of origin, with some studies positing simultaneous origins of economic and financial crises while others suggest a chronological shift indicating potential causality. The emerging evidence supports robust bidirectional causality between financial and real difficulties, with financial shocks transmitting to the real sphere and economic difficulties manifesting back in the financial sector.
Markets, Decision-Makers, and People
The human dimension is central to financial causality, because market behavior ultimately reflects the decisions of investors, firms, and policymakers operating under uncertainty. Causal claims influence trading strategies, portfolio allocations, and regulatory responses, meaning their accuracy carries real economic stakes for those who rely on them. Evidence that financial shocks propagate into the real economy, and vice versa, suggests these effects reach well beyond Wall Street into employment, output, and household welfare. For practitioners, the practical consequence is a healthy caution about any single, clean causal story in the markets.