
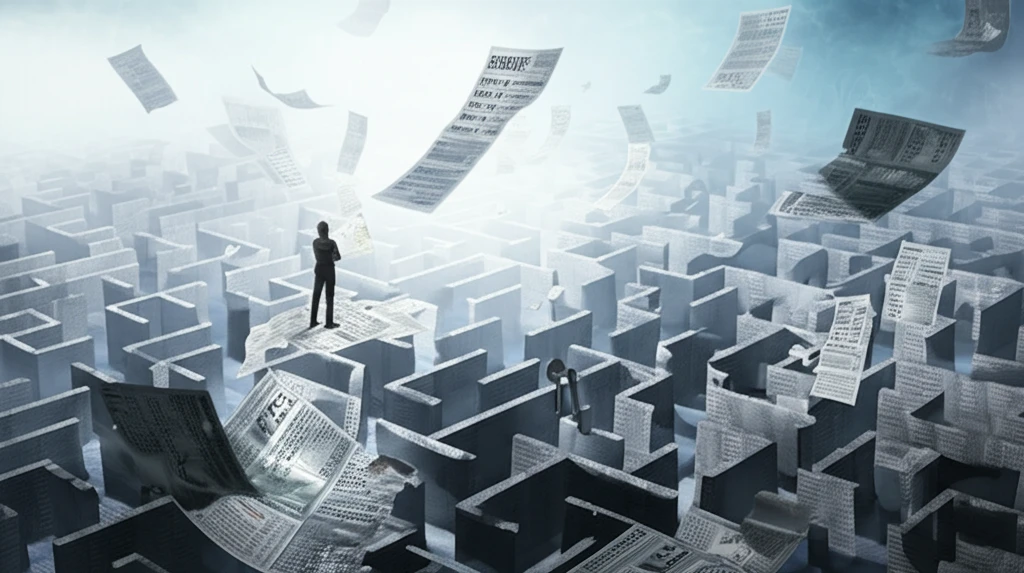
Decoding Disclosure: How Narrative Complexity Impacts Your Investments
"Unraveling the linguistic maze of financial statements to protect your portfolio."
Financial statements are the primary way companies communicate with investors, offering both quantitative data and qualitative explanations. Ideally, these disclosures should provide a clear picture, aiding informed decision-making. However, the language used in these narratives can be complex, sometimes intentionally so, obscuring vital information and making it harder for investors to understand a company's true financial health.
This article delves into the challenges posed by complex narrative accounting disclosures. We will explore how companies might use complicated language to mask negative performance, a practice known as 'management obfuscation.' Understanding these tactics is crucial for investors looking to make sound judgments and protect their investments.
Think of this as your guide to cutting through the corporate jargon. We’ll break down the research, reveal the key findings, and provide actionable insights to help you navigate the world of financial disclosures with confidence.
The Numbers Behind Disclosure
Federal campaign finance data published by the FEC shows how candidates and committees raise and spend money in federal elections, helping voters make informed decisions. At the global level, the World Bank provides free and open access to development statistics through its World Development Indicators. Even statistical agencies treat disclosure itself as a risk: under the FSRDC handbook, a disclosure avoidance review is required before any output is removed from a Federal Statistical Research Data Center. Research on voluntary disclosures between 2018 and 2022 found disclosure levels at 33.3%, with financial performance, measured by return on assets, ranging from -1.240 to 0.466.
Frameworks, Flexibility, and Their Limits
IFRS Sustainability Disclosure Standards, developed by the International Sustainability Standards Board (ISSB), set out the common approach to sustainability reporting. Under IFRS S2, companies follow a framework for disclosing climate-related risks and opportunities that is aligned with financial reporting. Such climate-related disclosures emphasize forward-looking, narrative, and qualitative information alongside relevant metrics and targets. Yet the accepted approach has limits: the earlier IAS 1 standard allows flexibility in presentation, which often leads to inconsistencies across companies.
From First Filings to ESG Milestones
Personal filings show how far disclosure requirements reach: Alexandria Ocasio-Cortez's first congressional disclosure, covering 2017 and 2018, reported just $3,003 to $45,000 in financial assets and the same $15,001 to $50,000 range on the liability side. On the institutional side, EU rules now govern how financial market participants and financial advisers must communicate sustainability information to investors. ESG investing itself has a long timeline of rules and practices that have shaped business strategy, and venture capital disclosure practices trace back to the industry's 1940s origins.
The Obfuscation Game: Hiding Behind Complexity
The central idea we're exploring is that companies sometimes make their financial disclosures deliberately hard to understand. Why? To hide negative information, particularly when the company isn't doing well. This strategy, termed the 'management obfuscation hypothesis,' suggests that complex language serves as a smokescreen, slowing down market reactions and potentially misleading investors.
- Readability Matters: Studies show that firms with lower earnings tend to have less intelligible annual reports.
- Investor Impact: Complex language increases the cost of information processing, making it harder for investors to accurately assess a company.
- Global Phenomenon: Research indicates this practice isn't limited to English-speaking countries; it can be found in various markets.
Filings and Findings in the Spotlight
The 927-page annual financial disclosure report released by the Office of Government Ethics for President Trump covered an array of investments, from Domino's Pizza and Costco to Victoria's Secret, Lockheed Martin, and large banks like JPMorgan. By contrast, Representative Ilhan Omar's latest disclosure reportedly listed the couple's assets between $20,000 and $125,000, with debts between $30,000 and $100,000, which would suggest a possible negative net worth. Beyond politics, a Duke study of research involving humans reveals reluctance to make financial disclosures, with officials disagreeing on how best to disclose information, including whether researchers should name the source of their funds.
Pushback and the Limits of Disclosure
Public comments on the SEC's proposed climate disclosure rules revealed a diversity of views, including suggestions to limit disclosures to material value chain emissions and to remove the quantitative threshold for materiality. Most commenters did not simply offer criticism or support; many proposed solutions to perceived problems or asked for additional disclosures. The limitations of disclosure also surface in performance claims, where regulatory disclaimers note that hypothetical or simulated performance results have certain limitations under CFTC Rule 4.41.
Side-by-Side: Rules, Markets, and Narratives
The SEC's Pay Versus Performance Disclosure Rules require three new elements: prescribed tabular disclosure, additional comparative disclosure that can be presented in graphical or narrative form or a combination, and a tabular list of financial metrics. Cross-border comparison is a well-established lens for judging disclosure quality, as a study of financial instruments disclosure found that comparability is one of the characteristics of high-quality financial statements, illustrated by comparing Indonesian and UK listed banks. Narrative disclosures are also being compared across domains, including how they appear in both financial and sustainability reporting.
Protecting Yourself: Strategies for Savvy Investors
So, what can you do to navigate this landscape of potentially misleading disclosures? The key is to be aware of the possibility of obfuscation and to take steps to ensure you're getting a clear picture of a company's financial health. Demand transparency, diversify your sources, and seek expert advice. By staying vigilant and informed, you can minimize the risk of being misled by complex narratives and make more confident investment decisions. Don't let corporate jargon cloud your judgment; empower yourself with knowledge and critical thinking.
Expert Interpretation of Financial Disclosure
Who interprets disclosures matters: experts are specifically designated to render professional opinions within their area of expertise, while lay witnesses are generally not permitted to offer expert opinions, and disclosure requirements apply to both roles. In family law, financial issues are often the cornerstone of dissolution of marriage cases, which is why judges and attorneys rely on financial expert guides. On the analytical side, new supplier finance disclosures proposed by the IASB help analysts calculate more realistic measures of cash flow, leverage, and working capital.
Environmental Disclosures as a Financial Compass
Environmental disclosures increasingly serve as lenses revealing a company's future readiness, and they are being positioned as a financial compass for long-term narratives. The IPSF report documents the state and trends of ESG disclosure policy measures across its member jurisdictions, Brazil, and the United States, underscoring how policy is converging globally. Regular economic outlooks, such as the IMF's World Economic Outlook survey of prospects and policies published twice a year, provide the macroeconomic backdrop for these disclosures. Real-time news platforms now track SEC filings, earnings, and dividends, making corporate disclosure a continuous, data-driven feed rather than a periodic event.
Disclosure Inside the Financial System
The financial system's challenges and opportunities can be understood through three interconnected aspects: financial institutions, regulation, and technology. Within this system, disclosure is becoming a tool for systemic impact, as Wise's first Impact report shows how sustainability and social impact tie directly into the company's mission of making international money transfers affordable, fair, and simple. Such reporting reflects how individual firms are embedding disclosure into the broader regulatory and institutional environment.
When Disclosure Meets Daily Life
Forward-looking financial disclosure can be uninformative if it does not change from the previous year, especially after a significant change in firm performance, and a study examined whether such disclosure responds to changes in firm performance. Related research on UK FTSE all-shares non-financial firms examined the impact of forward-looking disclosures on firm values. On a more personal level, financial disclosure sits at the center of most divorce cases, described as a formal process of exchanging documents, completing forms, and providing valuations, and it is here that problems begin to arise.