
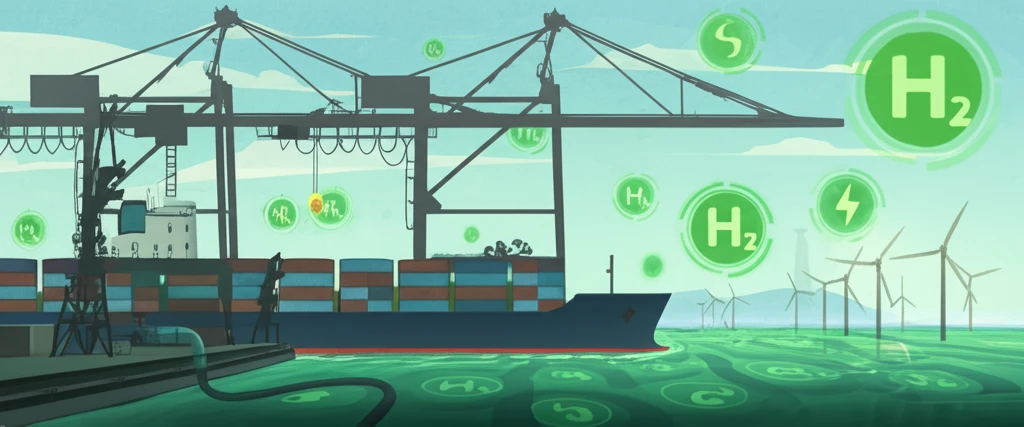
Can Shipyards Keep Up? The Looming Bottleneck in Global Hydrogen Transport
"A new study reveals potential shortages in shipyard capacity, threatening the expansion of maritime hydrogen transport. Is liquefied ammonia the answer?"
The global push to decarbonize energy systems is driving massive growth in renewable energy technologies. Yet, the most cost-effective renewable sources aren't always close to the biggest energy consumers. This is where maritime transport steps in, carrying low-carbon energy carriers like hydrogen and ammonia across the seas.
But here's the catch: can shipyards build enough specialized vessels to handle the expected surge in demand for these energy carriers? A recent study digs into this question, estimating future tanker demand based on global hydrogen projections and comparing it to historical shipyard output.
The findings reveal a potential bottleneck on the horizon, particularly if the world relies too heavily on liquefied hydrogen. This raises critical questions about how to overcome these limitations and ensure the smooth scaling up of maritime hydrogen transport.
A Nascent but Fast-Rising Shipping Demand
Reliable, public statistics on the global transport of low-carbon hydrogen are still thin, and widely circulated figures tend to be projections rather than measured cargo volumes. Most observers agree that international hydrogen trade is in its earliest commercial phase, with the bulk of movement happening inside a few producing regions. Because dedicated hydrogen-carrying vessels barely exist today, any specific number on future shipyard demand carries considerable uncertainty. The broad reading of the available reporting is that demand for hydrogen transport capacity will grow substantially over the coming decade, but by how much and how fast remains an open question.
From Baseline to Carrier-Based Shipping
The customary first step in moving hydrogen is to compress or liquefy it, since its low density makes unrestricted gas transport impractical over long distances. Current literature points to cryogenic liquid hydrogen and hydrogen-rich carriers such as ammonia as the leading candidates for ocean shipping, each trading off energy efficiency against cost and safety. A recurring limitation is that virtually every option demands new or heavily retrofitted vessels, terminals, and handling equipment that the commercial fleet does not yet possess. Because no single method has become a clear industry standard, shipbuilders face uncertainty about which hull designs will actually be ordered at scale.
A Long Known Element, a Very New Cargo
Hydrogen itself has been studied for centuries, and the chemistry of the element is well established in any standard textbook. What is historically novel is the ambition to ship it across oceans in industrial volumes as an energy commodity. Earlier milestones in industrial gas handling and cryogenic technology provide some foundation, but they do not translate directly into large-scale hydrogen carriers. In that sense, the foundational discoveries belong to science, while the engineering of ocean-scale hydrogen logistics still lies ahead.
The Bottleneck is Real: What the Study Found
The study highlights a few key concerns: first, a potential transport bottleneck could emerge between 2033 and 2039 if liquefied hydrogen is the primary energy carrier. Second, the concentration of suitable shipyards in East Asia raises diversification worries.
- East Asia Dominance: The study pinpoints only 14 shipyards capable of constructing these specialized vessels, and they're largely concentrated in East Asia. This lack of geographical diversity creates vulnerabilities.
- Capacity Crunch: The analysis projects a potential shortage of up to 53 million cubic meters in transport capacity by 2035 if the world relies solely on liquefied hydrogen.
- Container Ship Competition: Increasing demand for standard container vessels could further strain shipyard capacity, hindering the maritime hydrogen transport scale-up.
The Chemistry Underpinning the Shipping Question
Hydrogen is the lightest and most abundant chemical element in the universe, constituting roughly 75 percent of normal matter, though it rarely exists in free form on Earth. Its atoms are deceptively simple, each consisting of a single proton bound by the Coulomb force to a single electron, while standard conditions see hydrogen as a colorless, odorless diatomic gas of H2 molecules. The earliest known chemical property of hydrogen is that it burns with oxygen to form water, which is exactly why its name derives from Greek words meaning 'maker of water.' These fundamental, uncontested properties explain both hydrogen's promise as a clean fuel and the core difficulty of transporting it: a light, flammable gas is extraordinarily hard to move cheaply by sea.
Cost, Safety, and the Case for Caution
Skeptics point to cost as the central obstacle: producing, storing, and transporting hydrogen is expensive relative to the fuels it would replace, and every additional handling step adds expense. The fuel is also highly flammable, a property that has historically made parties nervous about densely packed cargoes on long ocean voyages. Because hydrogen must be pressurized, cryogenically chilled, or chemically bound into a carrier before it can cross an ocean, each proven pathway carries meaningful efficiency and pricing penalties. The takeaway from this skeptical literature is that even where the chemistry works, economic viability and public acceptance are not yet assured.
Hydrogen Against Its Would-Be Rivals
When set against alternative energy carriers, hydrogen's dense but troublesome nature invites straightforward comparisons that analysts still debate. Ammonia and other derivatives offer easier liquefaction and safer handling but add energy-intensive conversion steps on both ends of the voyage. Pipelines look economical over short continental distances but cannot cross oceans, leaving ships as the necessary bridge between continents. Whichever carrier ultimately wins, the comparison suggests the real bottleneck is not chemistry but industrial capacity to build the right vessels in time.
Avoiding the Impasse: Solutions for a Smooth Transition
The study isn't all doom and gloom. It also points to potential solutions. Increasing local hydrogen production, utilizing pipelines, or embracing liquefied ammonia as an energy carrier could circumvent the bottleneck. Liquefied ammonia offers a particularly promising alternative, as it may be easier to transport and handle than pure hydrogen.
Capacity, Confidence, and the Missing Husks
Drawing the threads together, experts broadly agree that the constraints on hydrogen shipping are less scientific than they are logistical and economic. Shipyards already carry full order books for conventional vessels, so adding a new hydrogen fleet means competing for scarce construction slots, skilled labor, and capital. Commentary tends to conclude that national targets for hydrogen trade will only be credible if the shipbuilding pipeline and port infrastructure are expanded in parallel. The honest synthesis is that the technology is proven in principle while the industrial ecosystem needed to deploy it at scale is still being built.
First Movers and the Next Decade
The near-term outlook hinges on a small number of demonstration vessels and pilot corridors that are widely expected to test the economics before anything is scaled up. Projections vary, but the general expectation is that specialized hydrogen shipping will ramp up in fits and starts this decade, with the pace set by regulation, fuel prices, and investment decisions yet to be made. New frontiers such as onboard liquefaction, purpose-built carrier classes, and integrated port infrastructure remain promising but unproven at commercial scale. The likeliest trajectory is a gradual build-out led by a few pioneering operators, followed by a catch-up wave once the early economics are demonstrated.
A Bottleneck Inside a Larger Transition
The shipyard question cannot be separated from the wider energy transition, where grid decarbonization, hydrogen production, and end-use adoption all have to move in step. A systemic risk is that investments concentrate in production while transport, storage, and port facilities lag behind, leaving molecules stranded far from where they are consumed. Regulation and certification standards are still catching up, which adds lead time to every vessel order and terminal project. Viewed systemically, shipbuilding capacity is less a technical hurdle than a pacing item for the entire global hydrogen value chain.
Workers, Communities, and Stakes
Behind the tonnage projections sit real human stakes: shipyard jobs, port communities, and the livelihoods of workers whose skills must shift from conventional vessels to more specialized gas carriers. Coastal communities face both opportunity and risk, with hydrogen hubs promising industrial employment while raising genuine safety and environmental questions. The transition also has a timing dimension that is deeply human, since training crews, engineers, and inspectors takes years even after hulls are laid down. Any realistic account of the hydrogen shipping bottleneck ultimately has to measure it not just in ships but in the people required to build, crew, and regulate them.