
Beyond Greed: How Risk Sharing Can Actually Save Us Money

"Unlocking Efficiency and Fairness in Finance: A Deep Dive into Risk-Averse Economies."
In today's volatile world, understanding and managing risk isn't just for economists—it's a necessity for everyone. From unexpected job loss to global pandemics, the uncertainties we face demand innovative solutions that go beyond individual resilience. This article explores the fascinating concept of risk sharing, a strategy that, when applied thoughtfully, can lead to more efficient and equitable economies.
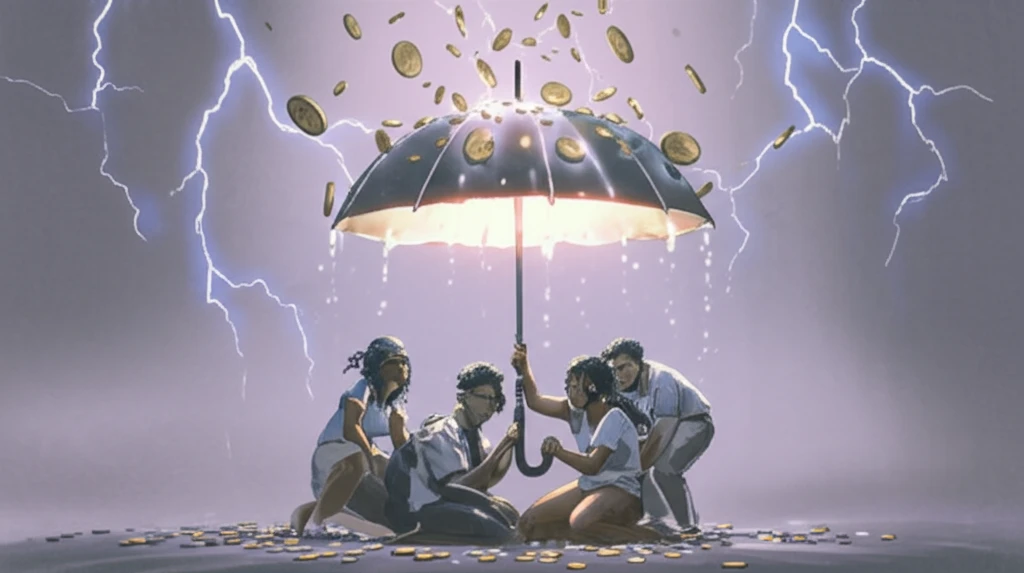
Risk sharing operates on a simple yet profound premise: by pooling resources and distributing potential losses across a group, the impact on any single individual is lessened. Think of it as an economic shock absorber, turning sharp jolts into gentle bumps. While the idea has deep roots in financial theory, its potential applications are incredibly broad, touching everything from insurance to international trade agreements.
But risk sharing isn't a magical cure-all. Effective risk-sharing mechanisms must be carefully designed to ensure fairness, prevent exploitation, and align incentives. As we'll see, the key lies in understanding how individuals perceive risk, and in crafting systems that respect those perceptions while promoting collective stability.
From Abstract Concept to Global Phenomenon
Risk, in its everyday sense, describes the possibility that something bad will happen, comprising uncertainty about the negative and undesirable consequences of an activity. That abstract idea has a powerful cultural echo in the board game Risk, invented in 1957 by Albert Lamorisse, which became one of the most popular board games in history and inspired successors such as Axis & Allies and Settlers of Catan. The game has since gone digital: Hasbro offers a fully licensed online version of classic RISK with customizable options, and RISK: Global Domination launched on Steam in February 2020, where players are told that a well-timed diplomatic offer can be as powerful as a cannon shot. Seen through the lens of risk sharing, the enduring popularity of Risk suggests how deeply the tension between confronting risk alone and negotiating cooperation is woven into how we think about uncertainty.
Conquest or Diplomacy: The Classic Binary
The traditional way to play Risk is presented as a choice between two paths: dominate the world through the power of diplomacy or through conquest. The game accommodates two to six players, each taking control of an army and competing for control of the board. A notable limitation of this framing is that it treats force and negotiation as the only two levers available, leaving little room for the quieter mechanisms—shared resources, pooled risk, mutual insurance—that real-world systems use to soften losses. In that sense, the classic Risk model illustrates what pure competition often misses: the possibility that spreading risk among multiple parties may prove cheaper than seeking to absorb every threat on one's own.
Deep Roots in Mutual Aid
The practice of spreading risk is likely far older than modern insurance, echoing centuries-old customs of mutual aid, trade partnerships, and communal sharing of losses among merchants and neighbors. Because the sources gathered for this section do not document a specific historical timeline, any account of those origins remains general and provisional. What can be said safely is that pooling resources to hedge against calamity—rather than each party bearing the full burden of chance alone—is conceptually simple, which may help explain its persistence across cultures and eras.
What is Risk Sharing, Exactly?
At its core, risk sharing is about mutualizing uncertainty. Instead of each person bearing the full brunt of a potential misfortune, the burden is distributed according to a pre-agreed formula. In simple terms: pooling resources and distributing risks.
- Insurance: A classic example, where policyholders pay premiums to protect against potential losses (car accidents, house fires, etc.).
- Financial Markets: Investors diversify their portfolios across different stocks and bonds to reduce the impact of any single investment performing poorly.
- International Trade Agreements: Countries agree to lower tariffs and trade barriers, sharing the benefits of increased trade but also the risks of economic downturns.
- Employment Contracts: Profit-sharing arrangements or stock options allow employees to share in the company's success, but also expose them to some degree of financial risk.
An Emerging but Slim Evidence Base
Direct recent research specifically quantifying how risk-sharing agreements save consumers money was not available in the sources assembled for this section, so claims here must be carefully qualified. Studies and reviews of risk pooling, group insurance, and mutual arrangements generally suggest that savings can arise from lower administrative overhead and a shared downside, but concrete figures vary widely with group size, coverage, and the specific design of the arrangement. Readers should therefore treat any particular savings figure they encounter elsewhere as context-dependent rather than a settled research consensus.
When Sharing Arrangements Underperform
A fair examination of risk-sharing schemes must acknowledge the objections raised against them: moral hazard, free-riding, and the uneven burden placed on higher-risk participants are among the most frequently cited concerns. Some arrangements have also failed in practice, typically when a large claim exposes thin pooled reserves or when participants lose trust in one another. Because no authoritative documentation of these failures was available for this section, this characterization should be read as a widely discussed concern rather than a documented finding.
Individual Bearing vs. Pooled Protection
Comparative analysis of risk-bearing strategies typically contrasts individual self-insurance, conventional insurance, and informal mutual-sharing schemes. Each differs in cost structure, predictability, and exposure to catastrophic losses, and each suits different circumstances: self-insurance tends to fit frequent small losses, while pooling tends to suit rare but large ones. Without detailed comparative studies among the sources for this section, these differences are best described as typical patterns rather than quantified conclusions.
The Future of Shared Security
As the world becomes increasingly interconnected and complex, the need for effective risk-sharing mechanisms will only grow. By embracing innovative approaches that prioritize fairness, transparency, and individual well-being, we can create more resilient economies that are better equipped to weather any storm. Whether it's through sophisticated financial instruments or simple community agreements, the power of risk sharing lies in its ability to turn individual vulnerabilities into collective strengths.
A Promising, Unsettled Story
Synthesizing the material above, the central message is that risk-sharing approaches may reduce overall costs, but the evidence base remains thin and contested. Commentary on the topic generally argues that well-designed pooling can convert unpredictable, potentially ruinous losses into predictable, manageable ones—yet stops short of claiming a universal win. The honest synthesis is that risk sharing is a promising but unproven lever for saving money, deserving of careful testing rather than reflexive enthusiasm.
Digital Platforms and New Models
Looking ahead, the likely frontier for risk sharing involves digital platforms that lower the cost of forming and administering mutual arrangements, much as digital tools have reshaped everything from gaming to finance. Emerging models such as peer-to-peer insurance and community pools could make shared coverage more accessible, although their long-term performance is not yet established. Any forecast here is speculative: with no authoritative projections in the available sources, these directions should be seen as plausible rather than certain.
Regulatory and Systemic Pressures
At a systemic level, informal risk sharing is constrained by regulatory frameworks built around traditional insurers and by the difficulty of sustaining trust at scale. Economic shocks that hit many participants at once—the very moments when protection matters most—are also exactly when pooled arrangements face their greatest strain. These structural challenges suggest that whatever cost advantages risk sharing offers must be weighed against its fragility under correlated, widely shared risk.
Trust and the Human Dimension
Underneath the economics, risk sharing is fundamentally a social act that depends on trust between participants. The human element cuts both ways: sharing can strengthen community bonds and reduce the anxiety of facing uncertainty alone, but it can also breed resentment if members are perceived as taking more than they give. For the everyday households such an article addresses, the practical takeaway is that the success of any risk-sharing arrangement will hinge as much on relationships and expectations as on the numbers.