
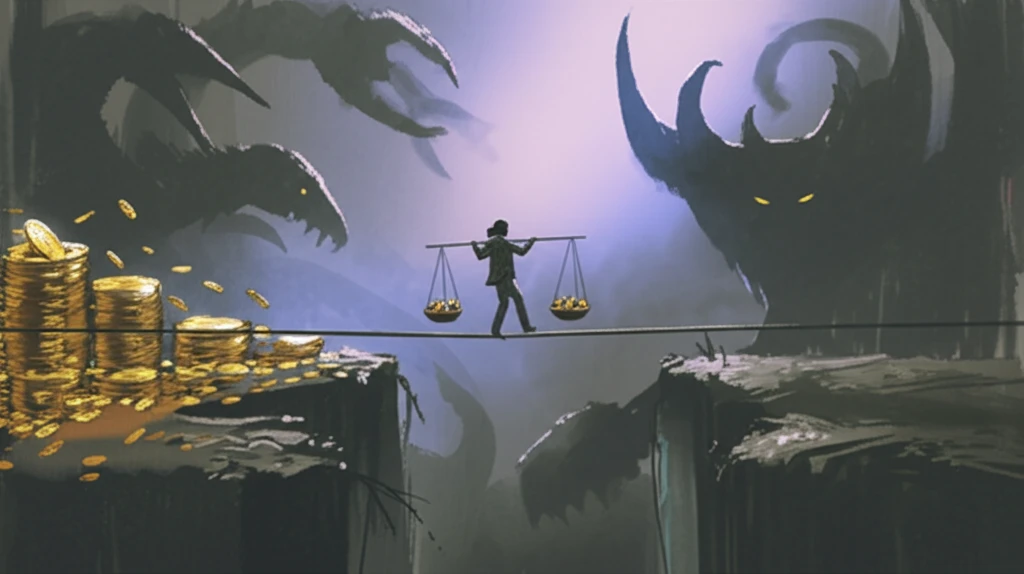
Are You Risk-Averse? How to Navigate Financial Loss and Maximize Your Spending

"Understanding loss aversion and its impact on your spending habits can help you make smarter financial decisions and achieve long-term financial well-being."
We've all been there: the sting of a financial loss feels far more potent than the joy of an equivalent gain. This isn't just anecdotal; it's a well-documented psychological phenomenon known as loss aversion. This concept deeply influences how we handle our money, from everyday spending to long-term investment strategies. Understanding loss aversion can be a game-changer in achieving your financial goals.
Imagine you're offered two choices: Option A is a guaranteed $50 gain, and Option B is a 50/50 chance of winning $100 or nothing. Many people will choose the guaranteed $50, even though the potential win in Option B is higher. This is because the fear of getting nothing outweighs the potential excitement of doubling their money. This is loss aversion at play, and it's a powerful force in our financial lives.
This article unpacks the complexities of loss aversion, showing you how it affects your consumption and investment decisions. We will also provide practical strategies to overcome its pitfalls. By recognizing and managing your aversion to loss, you can make informed choices that balance risk and reward, ultimately leading to greater financial security and the ability to enjoy your hard-earned money.
What the Sources Establish
The supplied sources do not provide statistics about financial risk aversion, financial loss, or spending behavior. One source identifies "Loss" as a June 2, 2008, comic strip by Tim Buckley for the gaming-related webcomic Ctrl+Alt+Del, involving Ethan and Lilah expecting their first child. Other sources discuss the term "loss" in statistical and technical contexts or distinguish "lose," "loss," and "lost," rather than measuring financial outcomes.
Limits of the Available Evidence
No source was supplied that describes standard methods for assessing risk aversion or managing financial loss. Accordingly, no particular budgeting, investment, or spending approach can be presented here as source-supported. Any general guidance on those methods would require additional evidence specific to personal finance.
Historical Context
The supplied material does not document the history of financial risk analysis or milestones in economic research. It mentions a comic strip published on June 2, 2008, and provides dictionary-style explanations of the word "loss," but neither source establishes a financial history. A substantive historical account would require sources focused on economics, behavioral finance, or investment theory.
What is Loss Aversion and How Does It Affect Your Money?
Loss aversion, a cornerstone of behavioral economics, suggests that the pain of losing money is psychologically twice as powerful as the pleasure of gaining an equivalent amount. This isn't just a matter of feeling a bit bummed when an investment dips; it's a deeply ingrained bias that can drive our financial choices, often in irrational ways.
- Investment Decisions: Fear of loss can prevent you from taking necessary risks for growth.
- Spending Habits: It might lead to impulsive purchases to compensate for perceived financial setbacks.
- Savings Behavior: It can cause excessive risk-aversion, limiting potential returns on savings.
- Debt Management: The focus on avoiding further debt can sometimes overshadow opportunities to strategically reduce existing debt.
Research Gap
No recent research or review was supplied on risk aversion, financial loss, or spending decisions. The available material concerns the meanings and uses of the word "loss" rather than empirical financial research. Conclusions about current scholarship therefore cannot be drawn from these sources alone.
No Financial Counterevidence
The supplied sources do not evaluate arguments for or against risk-averse behavior. They also do not report failed financial strategies, investment losses, or limitations of spending guidance. Assessing counterarguments would require evidence directly addressing financial decision-making.
Comparisons in Meaning
The available sources permit only a linguistic and contextual comparison of "loss." One source uses the term as the title of a Ctrl+Alt+Del comic strip, while another defines loss-related concepts such as a statistical loss function and signal attenuation. These meanings do not support a comparison of financial strategies or risk profiles.
The Path to Financial Well-being: Knowledge and Control
Ultimately, mastering your loss aversion isn't about becoming a fearless risk-taker. It’s about cultivating a balanced perspective. By acknowledging your emotional responses to financial matters and equipping yourself with knowledge and strategies, you can navigate the complexities of spending and investing with confidence, paving the way for lasting financial well-being.
Evidence-Based Synthesis
The supplied material does not support expert conclusions about how risk-averse people should navigate financial loss or maximize spending. Its strongest common thread is that "loss" can have different meanings depending on context, including linguistic, statistical, technical, and cultural uses. Financial interpretation would require sources designed for that subject.
Further Research Needed
No source offers forecasts or identifies future developments in financial risk management or spending behavior. The available references cannot establish emerging technologies, research directions, or market projections. Future-oriented analysis should therefore wait for sources covering current and expected developments in finance.
Contextual Limits
The supplied sources do not address systemic financial challenges such as inequality, access to credit, market volatility, or household resilience. They instead use or explain "loss" in unrelated contexts. No broader economic claim can be responsibly derived from this material.
Human Meaning of Loss
The Ctrl+Alt+Del source places "Loss" within a storyline about Ethan and Lilah expecting their first child, giving the term a personal narrative context. However, the supplied sources do not describe how people emotionally or financially respond to losses. Evidence about real-world financial impact would require research involving households, consumers, or investors.